
Cameco Weighs Quarterly Report Against Nuclear Boom
Cameco's third quarter showed $43 million of net earnings, a small adjusted net loss and $267 million of adjusted EBITDA.
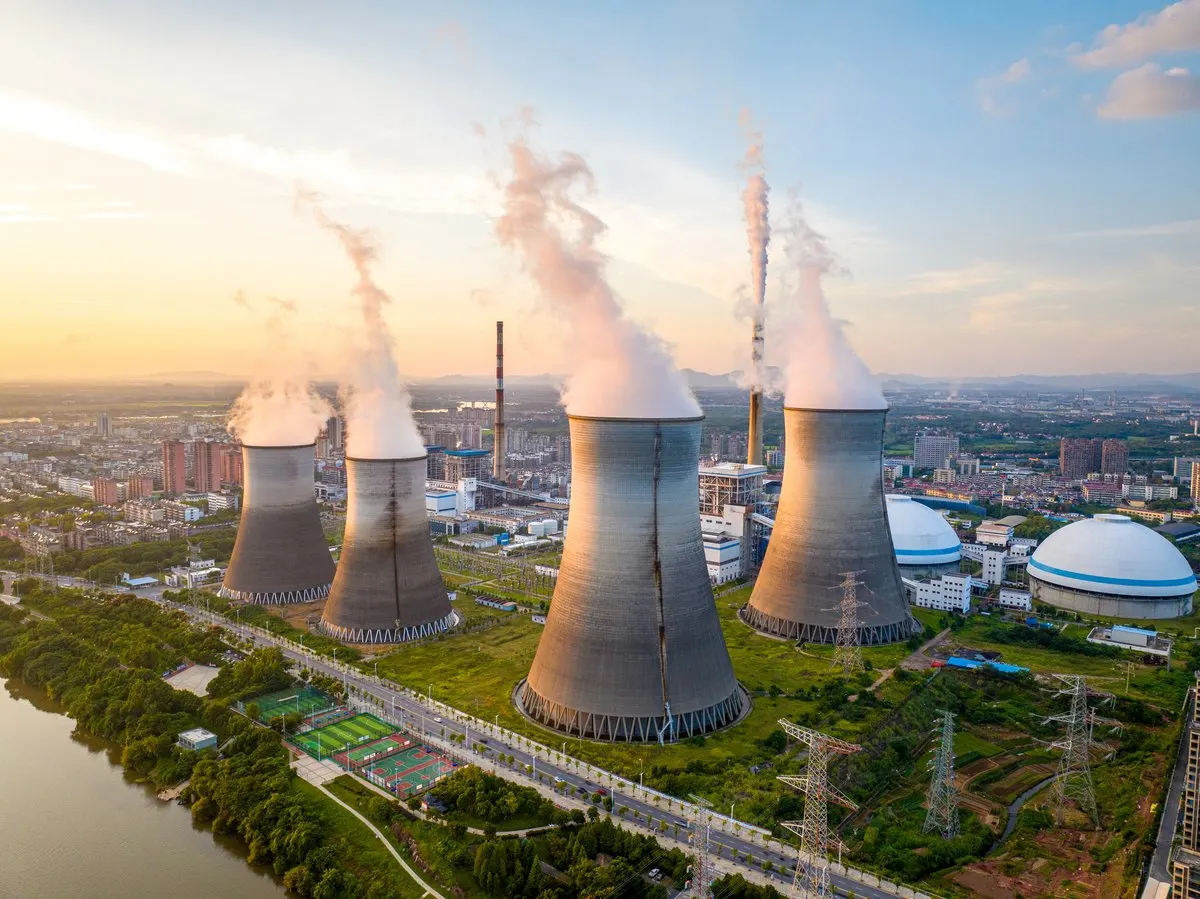
Cameco, the world's largest publicly traded uranium producer, reported third-quarter net earnings of $43 million, an adjusted net loss of $2 million and adjusted EBITDA of $267 million, in a quarter that looks unremarkable on its face but lands in a market whose expectations for nuclear fuel have shifted dramatically.
The gap between the three numbers is the story of the quarter. Net earnings measure the accounting result, adjusted net loss strips out items such as non-cash price-related effects and tax movements, and adjusted EBITDA shows the operating engine before financing and depreciation. A company can show a modest GAAP profit, a small underlying loss and solid cash generation in the same three months, and Cameco's quarter is a clean exhibit of how those measures can diverge when a business is positioned in front of a structural-demand story but is not yet collecting the prices that story implies.
Why the uranium market expects more than this
The weight behind Cameco's share price does not come from its current earnings. It comes from the position the company occupies in an industry where demand for nuclear fuel is rising faster than supply. Utilities, governments and, increasingly, power-hungry data-centre operators have committed to nuclear capacity, while the uranium mines that could feed those reactors take the better part of a decade to licence, build and ramp.
That asymmetry is why investors tolerate quarters in which reported profit is modest or slightly negative on an adjusted basis. Contract prices under long-term sales agreements reset slowly, and the market's bet is that the resets of coming years will pull realised prices up toward the spot environment, widening margins without any new growth spending. The third quarter simply provides a benchmark of what the company earns at today's realisations, not a projection of tomorrow's.
What the balance between measures says about execution
The adjusted net loss of $2 million deserves a second look, because it suggests that once the noise is removed, the quarter's operations and sales barely broke even. For a company whose investment case rests on leverage to rising uranium prices, that is not alarming by itself; long-term contracts shield realised prices from spot moves and postpone the benefit. It does, however, mean the operating result this year still depends heavily on how those contracts reprice.
Adjusted EBITDA of $267 million gives a fuller picture of cash generation. In a business with heavy fixed costs and high margins at the satellite, EBITDA levels of this kind provide the room to keep building the production and exploration programme while the pricing cycle turns. Investors who want to read the quarter's quality should watch that measure and realised contract pricing across the year rather than any single net line.
Nuclear expansion widens the customer list
Nuclear power is re-entering energy policy conversations where it had been retired. New build programmes in Europe, Asia and the Gulf, life extensions of existing reactors and the declared interest of technology companies in firm, carbon-free baseload power all expand the addressable demand for fuel.
For African economies, that policy shift has two practical consequences. Countries building or considering nuclear generation, including Nigeria's own long-considered programme, will find the fuel supply and engineering capacity that exists being committed to buyers several years ahead, which raises the importance of early contracting. And uranium production, which requires capital, logistics and governance standards at a level only a handful of countries can meet, becomes more strategically relevant, changing the economics for African countries with the geology, particularly southern neighbours already hosting production.
Placement of the quarter in a longer cycle
The caution behind the headline is that the company's outsized valuation presumes pricing conditions that have not yet arrived in its financial statements. The signatures that would confirm the transition are well understood: renewed large-scale long-term contracting, realised prices climbing toward recent spot levels, conversion and enrichment service agreements repricing, and steady operational performance at the mines.
The third quarter provided little new evidence on any of those signatures, which is why the market's judgement about the stock did not turn on it. What it did solidify is the operating context through which the next several quarters will be interpreted. When futures open with new deliveries and the contracts written during the present wave of demand come into effect, the numbers being compared against quarterly earnings will look substantially different from the modest sums collected this autumn, and the quarter as just delivered will be remembered mostly as the boom's backdrop rather than as a measure of the boom itself.
Up next
Exelon Points Utility Growth Through Third-Quarter Profit
Exelon reported third-quarter adjusted earnings of $0.87 versus $0.70 GAAP and tightened 2026 guidance to $2.85 to $2.91.
More in Corporate
See all
Caterpillar Lifts Sales as Operating Margins Widen
Caterpillar reports stronger third-quarter sales, higher operating margins and substantial operating cash generation.

Merck Raises Outlook as Oncology Sales Advance
Merck increases its sales outlook after third-quarter growth in oncology, animal health and newer medicines.
Secure Electronic Technology Q3 Revenue Falls 15.5% as Quarterly Loss Doubles
The listed lottery operator reported revenue of N920.7 million for the third quarter against N1.09 billion a year earlier, with a loss after tax of N105.8 million and accumulated losses of N2.92 billion against equity of N3.48 billion.
About the author
Emeka Okafor
Technology Reporter
Emeka Okafor writes for BusinessPress.
More by Emeka Okafor


