
Chicago Manufacturing Eases to 55.3 in October
The Chicago purchasing managers' barometer fell to 55.3 in October from 58.8, still in expansion but below expectations of 56.1.
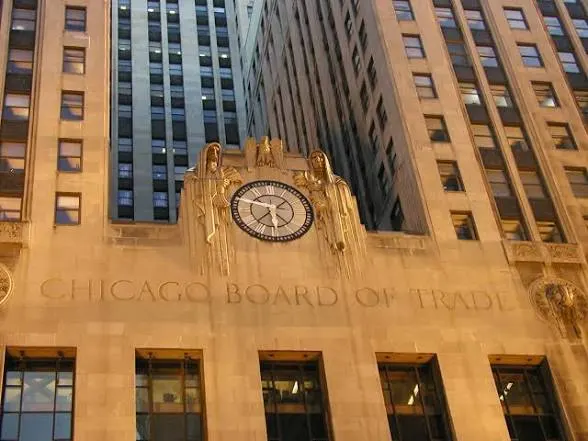
The Chicago Business Barometer fell to 55.3 in October from 58.8 in September, according to the purchasing managers' survey released on 30 October, remaining comfortably in expansion territory but slipping below economists' expectation of 56.1 for the month.
The Chicago survey is the oldest and most closely monitored of the regional reports that track American manufacturing, having run since the late 1960s, and its October reading still sits well above the 50 dividing line between activity growth and contraction. The pullback from September's strong figure is therefore a moderation signal rather than a deterioration, particularly since the index remains above its levels for most of the past two years.
The components tell the more useful story
This month's detail divides cleanly. Supplier deliveries dropped 10.3 points, employment gained 10.3 points, and prices paid rose 8.9 points, a combination that describes a manufacturing sector adjusting to unusually stretched logistics and stronger input costs while factories keep taking on workers.
Supplier deliveries mark the pace of manufacturing's supply chains, so the sharp pullback suggests the previous month's elevation of logistics delays is unwinding, which is a normal supplier pattern once a shock has been absorbed rather than a deterioration signal. On the other hand, employment rising strongly while prices paid also climb means factories continue to staff up while tariffs and other cost shocks are being passed through, and that combination matters for those tracking the wider economy's inflation environment in the months ahead.
What a strong manufacturing reading does to policy
The watch on regional surveys like Chicago's is predominantly for central-bank watchers, since purchasing-manager barometers of this type are behaving like indicators of the industrial cycle's turn, and this territory has inflated more recently than the national ISM reading in some months, making it useful to handle before the ancient practice of reading the month's actual industrial production figures
The Federal Reserve has cycle-changing considerations to manage, including markets' worries about the durability of the industrial rebound, and barometers like Chicago's offer monthly data which mainstream economists use to establish whether nationally-industry production is tracking broader purchase behaviour. A reading of 55.3, at the elevated end of recent years but off its September peak, leaves the discussion open: the industrial expansion is clearly under way, but the data hardly offers the central bank or the market anyone's confident expectations of a 2027 manufacturing boom.
Chicago's factories and the continent's industrial chains
The situation of regional manufacturing surveys like Chicago's, with an economy whose centre is not all industry, comes up in every emerging-market data regime as well. Nigeria's own PMI reporting has tracked the patterns of factories and energy supply, cost pass-through and employment cycles that the same survey covers, and the constant interplay of cost, orders and employment that sits under the Chicago figure is the underlying fabric of emerging-market industrial data cycles too.
For African producers with international exposure, the US manufacturing enlargement is a meaningful demand channel that determines orders for suppliers and raw materials, and this month's data shows it continues on its own, no longer as a technical rebound but as a generating force. Manufacturing's recent rise goes beyond just the mean of the industrial numbers, and its impact on the continent's commodity and manufactured-goods exports is a meaningful read for any business watching the global cycle from outside its own ranks.
How next month's surveys and signals stack up
A reading of 55.3, although below forecast, is the kind of print that provides the story of where manufacturing has landed rather than any new direction. The story moves on the details next month, with particular attention to whether the employment index holds its elevation and whether the prices-paid indicator keeps climbing, as that combination is the definition of a manufacturing cycle that hasn't yet crested.
What comes through for now is that the Chicago district's factories, along with a broader American industrial sector whose lead indicators have firmed over recent months, will finish 2026 in a state of growth that no survey of this type is claiming is less than substantial. What remains to be seen is the detail that separates growth from expansion, or expansion from acceleration, and the answers to both come in the coming months' readings rather than in today's number.
Up next
US Labor Costs Stay Near 3.4% as Services Bend
US employment costs rose 3.4% year on year in the third quarter, a fourth straight subdued reading that shapes Federal Reserve policy.
More in Economy
See all
Euro Forecasters Raise Near-Term Inflation Expectations
An ECB survey shows higher inflation forecasts for 2026 and 2027, while longer-term expectations remain at 2%.

Spanish Inflation Holds Steady as Price Pressures Persist
Spain estimates annual inflation at 4.9% in October, with offsetting movements across energy and other consumer prices.

US Growth Accelerates as Investment Strengthens
US GDP grew at a 3.4% annual rate in the third quarter, with investment strengthening while weaker exports restrained the expansion.
About the author
Tunde Balogun
Economics Correspondent
Tunde Balogun writes for BusinessPress.
More by Tunde Balogun
India GST Collections Jump 23% to Rs 2.31 Lakh Crore
Economy42 mins ago
Lagos Economic Roundtable to Shape 2027 Development Priorities
Business48 mins ago
BUA Foods Profit Rises Despite Lower Sales
Agriculture


