
China Factories Slip Back Below Growth Line in October
China's October manufacturing PMI fell to 49.3 from above 50 in September, with new orders at 49.4 and production at 49.8, NBS data shows.
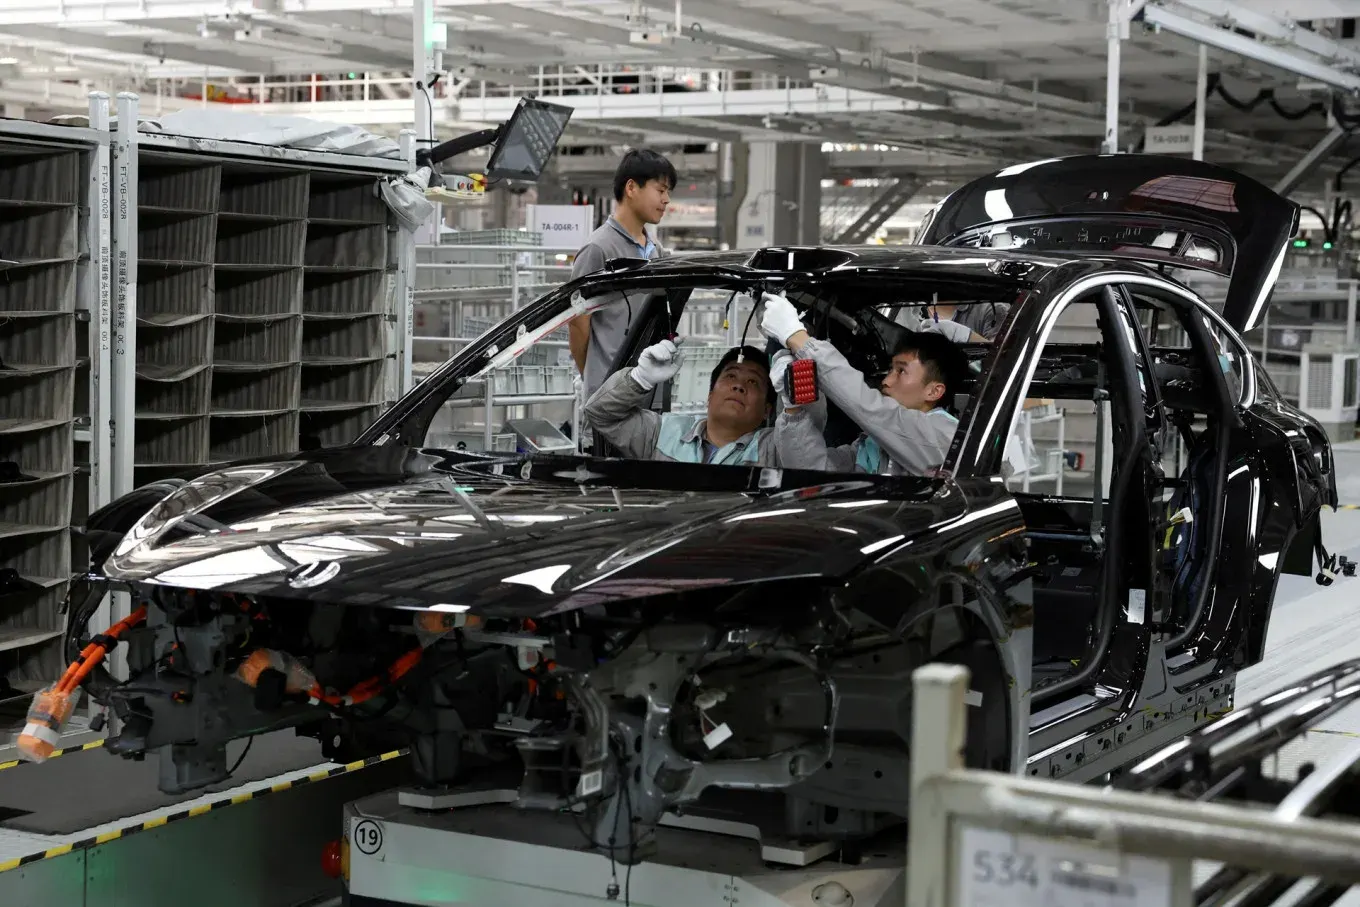
China's official manufacturing purchasing managers' index fell to 49.3 in October from 50.1 in September, according to the National Bureau of Statistics on 31 October, dropping the factory indicator back below the 50 level that separates expansion from contraction after a single month of improvement.
The details of the survey show a contraction in the breadth of activity rather than the depth of it. New orders fell to 49.4, production eased to 49.8, and the largest firms, those whose activities usually shape the overall reading, returned a reading of 50.2, still above the expansion threshold. The non-manufacturing index declined to 49.7 and the composite output index, which combines manufacturing and services, fell 1.0 points to 49.7.
The difference between one month and a trend
September's reading above 50 had prompted discussion about whether the economy's factory sector was turning upward as stimulus measures landed. October's reading rebounds that question: the index has moved back into contraction, meaning the underlying improvement that September appeared to show was not sustained.
The frequent pattern in Chinese industrial data, where a strong month produces expectations of a follow-on expansion and the next month falls short, is a function of the economy's structure and the policy calendar rather than of any major deterioration in the environment. What matters for observers is the direction of the previously identified trend, and after two readings, the trend sits between the two months' outcomes rather than matching either.
The policy calendar and what it still holds
October's figure arrives against a policy environment in Beijing that has been working to strengthen domestic demand through measures that support consumption, encourage infrastructure investment and relieve pressure on companies. The weakening data raises the probability of additional measures, particularly those that directly target household consumption.
The manufacturing indicator itself is not the sole statistic that guides policy, however. The services reading of 49.7 and the composite output index of 49.7 are as relevant, since the services sector has been the part of China's economy that policymakers have identified as the strongest candidate for a consumption-led expansion, and a services reading in contraction territory weakens the argument that the economy's structural shift toward services is progressing smoothly.
What the numbers imply internationally
The global implications touch commodity markets first. China is the largest buyer of iron ore, industrial metals and crude oil, and the direction of the country's factory activity is the strongest monthly signal for the demand expectations embedded in those prices.
For African exporters of commodities to China, the message from the October data is that the demand side has weakened rather than broken. The export flows that carry raw materials into Chinese factories respond to China's industrial production plans, and those plans are often set in the fourth quarter for the next year, which means the October data also feeds into the volume discussions for 2027 contracts across metals, minerals and energy.
The one-month framing matters for how the figure should be used. A single movement across the expansion line is not, on its own, evidence of a sharp slowdown in activity; it captures a marginal cooling rather than a contraction in real output, and the quarterly averages of these indicators have historically blended such swings. The risk in reading too much into October is the same risk that produced the September optimism, and both readings belong in the same judgement rather than either standing alone.
The signal before the next stimulus
As the fourth quarter begins, the figure that will matter for markets is not the one that arrived on Monday, but the next one, which comes after any policy response. As with the recent history of the Chinese economy, a disappointing PMI arrival produces stimulus announcements whose effects show up in the following quarter's data, and the reading for November will be the first that shows whether new measures are beginning to take effect.
What October has demonstrated is that the Chinese factory economy's demand-side recovery remains fragile, and the autumn-winter readings for the fourth quarter will determine whether the plateau that the September and October figures suggest proves to be a pause or a lower band. For now, the October figure captures the manufacturing sector resting flat after a single month back above the line, which is the most useful single description of the indicators released on Monday.
Up next
Africa Energy Bank Launches in Abuja to Close $200bn Gap
The Africa Energy Bank, launched in Abuja by Afreximbank and APPO, opens with $5 billion of authorised capital and a mandate to fund energy.
More in Economy
See all
Canada GDP Flat in August as Business Slows
Canada's real GDP stayed flat in August for a second straight month, with a September flash estimate of minus 0.1% rotating focus.

Taiwan Economy Grows at Fastest Pace in Decades
Taiwan's GDP rose 14.36% year on year in the third quarter, a four-decade record, driven by exports of semiconductors and AI hardware.

Euro Forecasters Raise Near-Term Inflation Expectations
An ECB survey shows higher inflation forecasts for 2026 and 2027, while longer-term expectations remain at 2%.
About the author
Adaeze Okonkwo
Markets Editor
Adaeze Okonkwo writes for BusinessPress.
More by Adaeze Okonkwo
Nigerian Stocks Post Record Week With N637bn Turnover
Markets1 hr ago
TAIEX Takes Two-Day Slide as Chip Earnings Circulate
Markets3 hrs ago
bp Reports Sharper Quarterly Profit and Strong Cash Flow
Corporate3 hrs ago


