MeCure profit rises 36% as marketing savings lift operating margin
Operating profit grew faster than revenue, but finance costs absorbed about half of that result as the company expanded its fixed assets.
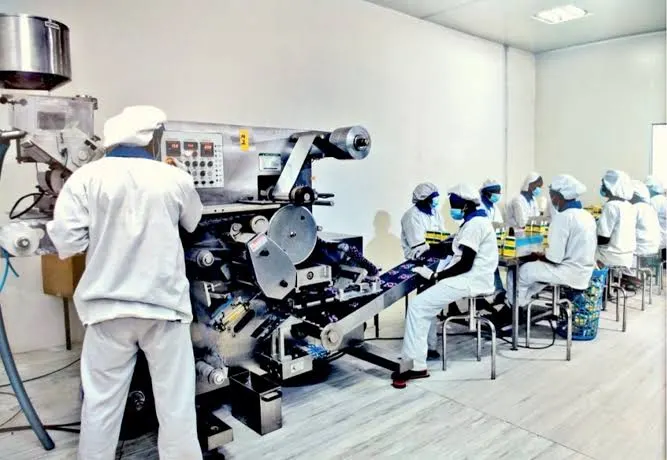
MeCure Industries increased nine-month profit after tax by about 36% to N6.05 billion, with lower marketing spending helping operating profit grow faster than revenue. Its interim results, disclosed through the Nigerian Exchange on 28 October, also show financing costs absorbing about half of operating profit.
The pharmaceutical manufacturer's result therefore combines an improvement in trading performance with a continuing funding burden. Investors assessing the growth need to distinguish the benefit from cost control from the expense of carrying the assets and working capital supporting the business.
Marketing savings help widen the operating margin
MeCure's unaudited statement reports revenue of N70.24 billion, against N60.01 billion, and operating profit of N17.49 billion, against N13.02 billion. Marketing expenses fell to N1.30 billion from N2.64 billion.
BusinessPress calculations put the operating margin at approximately 24.9%, compared with 21.7%. The reduction in marketing spending accounts for roughly N1.35 billion of cost relief before considering changes elsewhere.
Lower spending is a financial outcome, rather than proof that every marketing activity became more effective. Its durability depends partly on whether the business can maintain sales without needing to restore expenditure. The current figures show the benefit in this reporting period, not the long-term return from each promotional programme.
Gross profit improves without a dramatic margin shift
Gross profit rose to N24.13 billion from N20.41 billion. Administrative expenses increased to N5.78 billion from N4.89 billion.
The gross margin was roughly 34.4%, compared with 34%. This is a modest improvement alongside revenue growth of approximately 17%. It suggests that a large part of the gross-profit increase came from the bigger sales base, while the wider operating-margin gain also relied on the expense mix.
The accounts do not establish an equivalent rise in the volume of medicines produced. Revenue can change with prices, quantities and product mix. For Nigeria's pharmaceutical sector, the result is evidence about one listed manufacturer's performance, rather than a direct measure of industry output or patient access.
Finance costs remain a substantial claim on earnings
Finance costs increased to N8.84 billion from N6.65 billion, leaving pretax profit of N8.64 billion. The financing charge was equivalent to about 50.6% of operating profit, BusinessPress calculates.
That relationship makes financing terms central to the amount shareholders retain. Stronger operating income can support more borrowing expense, but it does not remove the risk that refinancing or higher rates absorb future gains.
For a manufacturer investing in capacity, borrowing can bridge the period before additional assets generate sales. The commercial test is whether the returns from those assets exceed their funding and maintenance costs. The earnings increase alone cannot settle that question for every investment made during the period.
The balance sheet shifts between funding instruments
Commercial paper declined to N14.17 billion from N26.03 billion at December 2025. Non-current term loans increased to N26.68 billion from N14.69 billion, while property, plant and equipment reached N53.07 billion from N40.64 billion.
Those are comparisons with the year-end position. They show a change in funding composition rather than proving that the overall financing burden disappeared. Different instruments carry different repayment dates and conditions.
Moving part of financing away from short maturities can change refinancing exposure, but the actual benefit depends on the new terms. No interest rate or repayment schedule is inferred from the balance-sheet totals. The larger fixed-asset base also needs productive utilisation before its economic return can be assessed.
The filing's status and payout language need care
The report is headed as unaudited, although some standard certification wording refers to audited statements. It also leaves the exact board-approval date blank. The disclosure date is therefore used here without inventing a signing date or treating the interim figures as audited accounts.
The directors say they do not propose a dividend for this reporting period. That statement is distinct from the treatment of earlier distributions in the equity accounts.
The next substantive test is whether the expanded asset base supports collected sales while financing charges remain manageable. The current result shows stronger operating and net earnings, accompanied by enough financial expense to make the cost of funding a central part of the investment assessment.
Up next
Nigerian Breweries profit rises 33% as financing costs ease
A wider gross margin and lower net finance costs lifted earnings, while third-quarter revenue declined and distribution expenses increased.
More in Corporate
See all
First HoldCo pre-tax profit rises 60.84% to N911.24 billion
Strong interest income and lower provisions lifted First HoldCo’s nine-month profit, boosting dividend expectations and bank-sector sentiment.
Unilever Nigeria posts N184 billion Q3 revenue and N26.4 billion profit
Unilever sustained profitable growth despite consumer pressure, declaring an interim dividend as pricing and cost controls protected margins.
Secure Electronic Technology Q3 Revenue Falls 15.5% as Quarterly Loss Doubles
The listed lottery operator reported revenue of N920.7 million for the third quarter against N1.09 billion a year earlier, with a loss after tax of N105.8 million and accumulated losses of N2.92 billion against equity of N3.48 billion.
About the author
Fatima Bello
Analysis Editor
Fatima Bello writes for BusinessPress.