
NAHCO Grows Nine-month Profit 19% to N16bn
NAHCO lifts nine-month profit after tax 19.2% to N16.04bn with Q3 revenue up 16.5% to N55.64bn as aviation handling and logistics demand expands.
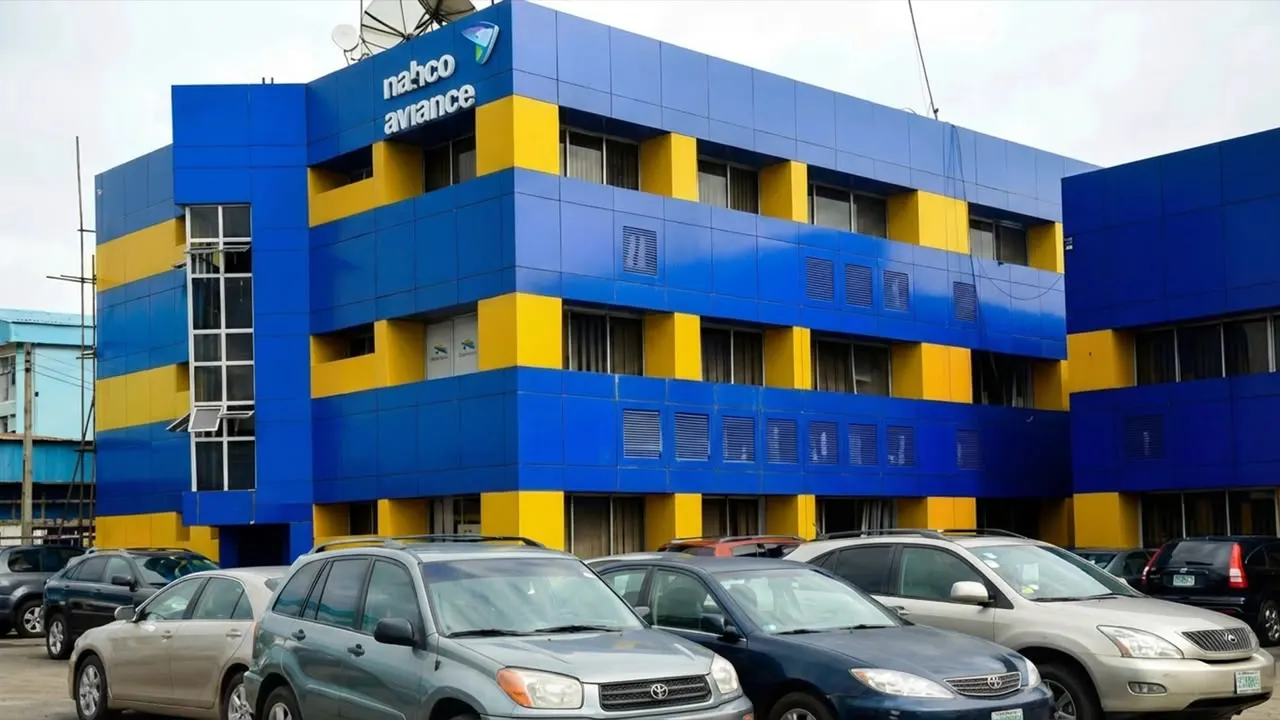
Nigerian Aviation Handling Company (NAHCO) has lifted nine-month profit after tax by 19.2 per cent to N16.04 billion, consolidating its position as West Africa's dominant aviation ground-handling and logistics operator, according to its unaudited interim results released Thursday on the Nigerian Exchange. Third-quarter revenue rose 16.51 per cent to N55.64 billion from N47.76 billion a year earlier, with operating profit up 19.5 per cent and earnings per share climbing to N7.20 from N6.04.
The print is significant because it shows sustained double-digit expansion at a company whose fortunes are tied to passenger volumes and cargo throughput — the two categories most leveraged to Nigeria's air travel recovery and the year's import-export cycle. NAHCO's result continues a run of consecutive improvements that has also underpinned six years of higher shareholder dividends.
Efficiency gains behind the earnings
The quality of the earnings matters as much as the headline growth. Operating profit grew faster than revenue — 19.5 against 16.51 per cent — indicating improving operating margins rather than mere volume expansion, a direction management attributes to brand preference and operational efficiency. Finance costs fell 19.7 per cent to N1.26 billion, cushioning a steep 39.1 per cent drop in finance income, and pre-tax profit rose 18.39 per cent to N21.24 billion.
The declining finance-cost line is overlooked in most coverage of the result but deserves emphasis. As the company deleverages, its earnings composition shifts from financial quirks to core operations, changing valuation dynamics: the market typically awards operations-led profit growth a higher multiple than financial income growth, because the underlying business is more durable and repeatable.
Aviation as a structural growth channel
NAHCO's growth is set against an aviation backdrop in which Nigeria remains West Africa's largest travel and cargo market. Ground handling is a high-barrier, capacity-constrained business: licences, equipment fleets, warehousing and trained labour take years to assemble, and competitors face heavy start-up economics. As long as air traffic expands — driven by increased international routes, domestic capacity growth and the air-cargo growth through hubs like Lagos and Port Harcourt — the incumbent handler rides the volume without needing to raise prices aggressively.
There is also the import-cycle angle. Nigeria's rising FX throughput, with official-market utilisation hitting $18.3 billion in the second quarter, means more cargo cleared, stored and handled — NAHCO's logistics and warehousing segments capture value along the chain. When imports grow alongside the export push, air-cargo revenue rises even without fare increases, adding an inclusionary earnings kicker to an already well-structured business.
Dividend trajectory is the market's focus
The market will read Thursday's numbers primarily through the dividend lens. Third-quarter dividend cover stands at 1.15 times, up from 0.97 times for the comparable 2025 period, even after a bonus issue increased the outstanding share count — headroom that the company's board can convert into higher payouts for a sixth straight year. That trajectory matters because NAHCO's shares have been one of the Nigerian Exchange's strongest mid-cap performers since 2024, and shareholders have increasingly priced the stock as an income-plus-growth compounder rather than a trajectory wonder.
On the verification side, the result's clean structure — revenue, operating profit, pre-tax profit and net profit all rising within a few percentage points of each other, and finance costs falling — speaks to operational, not accounting, momentum. There are no unusual one-offs in the released numbers, which means the market has no earnings-quality discount to apply.
What it signals for the wider logistics sector
For investors scanning the Nigerian industrials and services complex, NAHCO's print strengthens the case of logistics-adjacent names generally. The structure of the business — inflation-linked tariffs, high fixed-asset barriers, expanding cargo volumes and improving spreads — is the same profile that industrial and logistics operators across emerging markets have ridden to re-ratings over the past two years. Peer logistics and maritime names have also printed strong interim numbers during this earnings season.
The risks are cyclical rather than structural. Deterioration in international air traffic — whether from oil-driven fare inflation, geopolitical disruption, or travel-watcher sentiment — would clip the passenger segment, while any FX-driven slowdown in import categories would soften air cargo. The fuel story is the practical instance: with the Dangote Refinery raising gantry prices to N1,300 per litre and airlines' kerosene costs tracking crude higher, aviation economics get harder in a period of rising fuel costs — costs that handlers generally pass through but which still squeeze airline demand.
Positioning into year-end
Coming into the traditionally fourth-quarter peak in travel, cargo and holiday logistics, NAHCO enters the strongest season of its calendar with double-digit momentum and dividend headroom intact. For a market still digesting this week's N3.28 trillion value swing on the NGX, names with consistent underlying earnings and no accounting volatility have become the defensive allocation of choice — and Thursday's result positions NAHCO squarely in that cohort.
Up next
Lam Research Bets $25bn on AI Trade Settlement
Chip equipment maker Lam surges 8.2% after unveiling a buyback of up to $25bn, the sharpest confidence signal yet inside the AI hardware chain after a $3trn rout.
More in Corporate
See all
MTN Nigeria Nine-Month Profit Climbs 55 Percent
MTN Nigeria grew nine-month profit after tax 55.3 percent to N1.17 trillion as data revenue surged 35.8 percent and cash tax payments jumped to N295.4 billion.

Dangote Cement posts nine-month profit of N974.8 billion as the stock extends its rally on record monthly volumes
Dangote Cement reported nine-month 2026 profit after tax of N974.8 billion, up 31.2 per cent year on year, on revenue of N3,774.2 billion, while its shares on the Nigerian Exchange extended gains into Thursday's session.
Secure Electronic Technology Q3 Revenue Falls 15.5% as Quarterly Loss Doubles
The listed lottery operator reported revenue of N920.7 million for the third quarter against N1.09 billion a year earlier, with a loss after tax of N105.8 million and accumulated losses of N2.92 billion against equity of N3.48 billion.
About the author
Ngozi Eze
Companies Reporter
Ngozi Eze writes for BusinessPress.
More by Ngozi Eze


