
Markets Head Into US Midterm Vote, Yields in Focus
Investors head into the US midterm elections watching fiscal policy, Treasury issuance and sector leadership, with Democrats expected to win the House and a heavy earnings week ahead.
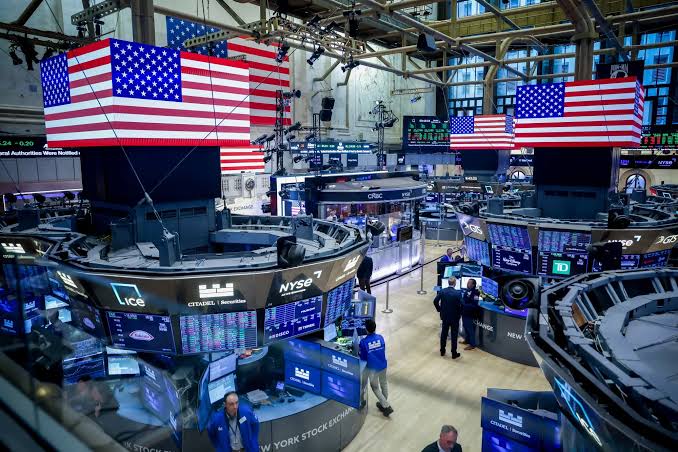
US investors head into Tuesday's midterm elections with federal policy, government borrowing and Treasury yields at the centre of the market's next directional debate, as voters get ready to decide whether Democrats can take back control of Congress from the Republican Party in the final political test of the administration's first half.
The setup is well telegraphed. Democrats were widely expected to win the House of Representatives, while the Senate outcome remained less certain heading into the final week, according to polling summaries carried by global market desks. Republicans have controlled both chambers during the first two years of the administration, and midterm elections have historically been unfavourable for the party in power — a pattern that frames why the market takes divided-government scenarios seriously as a base case rather than a shock.
What investors watch in midterms
The financial channels of a midterm for financial markets run through fiscal arithmetic. A divided Congress typically caps the scale of new fiscal expansion, slows big new spending programmes and raises the probability of debt-ceiling standoffs — each of which transmits into Treasury issuance, yields and dollar flows. With borrowing already heavy and the IMF flagging America's reliance on short-dated funding as a vulnerability this very week, the composition of the next Congress bears directly on the bond math that sets global discount rates.
Equities have their own midterm pattern: monthly performance around midterms historically improves as uncertainty resolves, and the S&P's October-into-November transition — this year a tech-rotation, not a bear move — has so far followed the seasonal shape rather than fighting it. The bigger question for asset allocators is sectoral: defence, energy and infrastructure names carry different exposures depending on which chamber the administration loses first.
The week's economic and earnings calendar
The vote sits inside a busy macro week: September JOLTS job openings arrive Tuesday, Thursday brings a Bank of England decision widely expected to raise rates, and Friday's US payrolls report is expected to show about 65,000 new jobs — up from 29,000 in September. Throughout it all, a full slate of corporate earnings keeps the tape honest, with Pfizer, Shopify, Eaton, Marathon Petroleum and Public Service Enterprise reporting before the open Tuesday and Advanced Micro Devices and Super Micro after the close — followed by Arm Holdings and Qualcomm on Wednesday.
The earnings context is strong, which matters for how markets absorb political risk. With 82 percent of reporting S&P 500 firms beating earnings estimates and aggregate EPS up about 29 percent among reporters, the fundamental backdrop is one in which midterms can reshuffle sector leadership without threatening the earnings cycle itself — historically the difference between volatile weeks and regime changes.
Reading the polls versus the tape
Sector futures and hedges have already moved on the polling picture: healthcare and infrastructure-adjacent groups rallied through October as investors priced the divided-government spending freeze that benefits grind-it-out business models, while some parts of tech — where regulatory posture is the swing factor — carry event-risk both ways. Betting markets and poll averages tightened through the final week, particularly on the Senate side, meaning Tuesday's prints will reprice rather than reveal.
For global investors, and for African market watchers whose sovereign curves borrow dollars priced off Treasuries, the practical transmission of the midterms is the fiscal-inflation bargain it seals. A smaller-deficit scenario is disinflationary and supports dollar bonds; the government-shutdown risk it creates is the offset. Both will be priced in the auction market's coupon valuations from Wednesday morning onward.
None of this makes Tuesday a single-stock event; it is a macro reset wrapped in an electoral calendar. The market's job this week is to absorb elections, payrolls, PMI releases and hundreds of earnings reports without breaking the rotation that has carried it into November — and the evidence so far is that cash is being paid for discipline: rotation, hedging and patience, not panic, in the week before Americans vote.
Up next
Okta to Join S&P 500, Replacing Kenvue
Okta rose 2.7 percent on news it will join the S&P 500 in place of Kenvue, triggering index-fund buying and marking a benchmark shift toward cybersecurity technology.
More in Markets
See all
TAIEX Takes Two-Day Slide as Chip Earnings Circulate
Taiwan's TAIEX lost 1,642 points on Friday after a 980-point fall the previous day, as investors reassessed the island's record AI-led run.

Wall Street Weekend Slide Puts Logic Behind Rates Habits
S&P 500 fell 1.82% and Nasdaq 2.86% on Friday as weak Intel guidance recharged worries about AI spending, payback and valuations.

ICE Revenue Rises as Market Services Expand
Intercontinental Exchange reports higher revenue and profit, highlighting demand for trading, risk management and financial data.
About the author
Abiodun Abdullahi
Author / Business and Markets Writer
Abiodun Abdullahi writes for BusinessPress.
More by Abiodun Abdullahi


