
Pivot Raises N100.08bn From Oversubscribed Commercial Paper Issuance
Pivot raised N100.08bn from an oversubscribed commercial paper issuance, a landmark scale for Nigeria's N1.61trn corporate CP market.
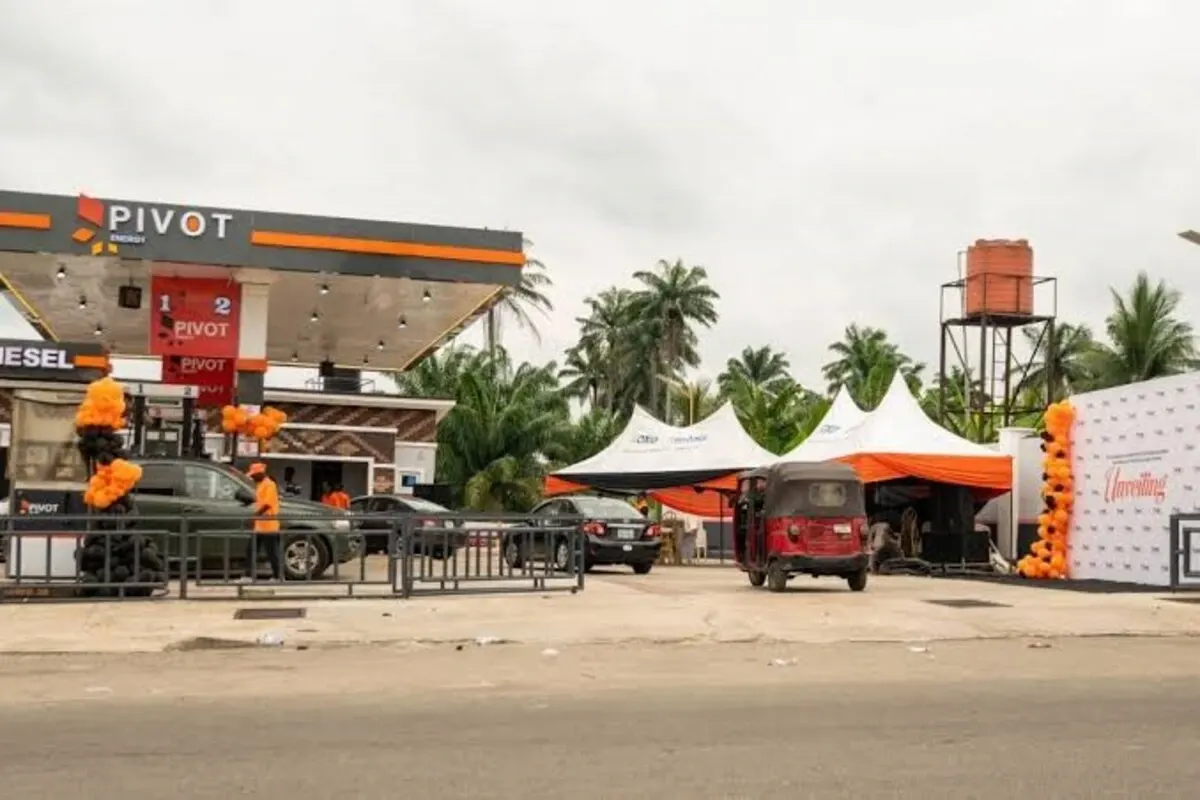
Pivot, the Nigerian logistics and energy services group, has raised N100.08 billion through a commercial paper issuance that was oversubscribed — the single largest tranche of evidence yet that Nigeria's short-term corporate debt market is willing to fund non-bank corporates at scale. The oversubscription, reported by BusinessDay, means investors demanded more of the paper than the company offered, a pricing outcome that tucks the issue into a select tier of Nigerian CP programmes this year.
The scale is what makes the issuance notable. A N100 billion single programme issuance is a sovereign-adjacent size for the Nigerian corporate market — larger than most bank bureaucracies would ever lend a trading company in one slice — and it arrived fully subscribed, meaning institutional money (pension funds, asset managers, corporate treasuries) allocated real portfolio weight to corporate credit risk rather than parking cash in T-bills. Nigeria's CP market grew 40 percent in 2025 to N1.61 trillion from N1.15 trillion, and issues of this scale are pulling the market's centre of gravity from boutique to institutional.
What oversubscription tells you about a market
An oversubscribed issue is the cleanest signal a debt market produces. It means the issuer cleared its pricing threshold — the discount rate at which investor demand exceeded supply — and that the market's allocators made a portfolio choice: this credit, at this price, is worth holding ahead of the alternatives. In Nigeria's current rate environment, where T-bill yields and money-market funds have hoovered institutional cash, every oversubscribed corporate issue is evidence that risk pricing has matured enough for the private-credit market to compete for institutional money on both yield and diversification.
For the issuer, the benefit compounds. A successful, oversubscribed programme has become a financing identity: it opens the next issuance at tighter pricing, it extends the tenor profile the market will accept, and it builds the ratings and disclosure record that make future, larger cheques possible. The corporate paper market rewards issuers who show up repeatedly with the same discipline — and N100 billion placements signal that the market can absorb scale when the story and the sponsorship are right.
The logistics-and-energy logic of the raise
The sector context for the issuer matters for risk assessors of all types. Nigeria's logistics and energy-services companies have become the operational backbone of the deregulated economy: fuel distribution chains, freight networks, storage and last-mile infrastructure — all of which carry heavy working-capital cycles, where the gap between paying suppliers and collecting from customers must be funded continuously. Commercial paper, with its 30-to-270-day tenors, matches that cycle precisely, and this is why trading and logistics companies have become natural issuers as the market has broadened beyond consumer-goods giants.
The funding mix of the economy also sits behind this deal. With commercial banks' loan books tilted to Treasury-bill arbitrage and consumer credit at spreads corporate borrowers dismiss, the CP market is now the main non-bank working-capital channel for mid- and large-cap Nigerian corporates. Every N100 billion raised off the CP rails is, in effect, proof-of-demand for a market structure that does not depend on bank behaviour — a structural shift as relevant to monetary policy as to the issuer.
What this means for the market's next phase
Nigeria's CP segment is now running at institutional scale: about N1.61 trillion raised in 2025, an average discount rate of 22.38 percent, an average tenor stretching to 233 days, and a growing cohort of non-consumer issuers financing logistics, energy services, technology and manufacturing. The winners of the next phase will be decided by two variables: how the rating agencies' output shapes the credit spectrum's pricing efficiency, and how quickly new issuers — mid-cap companies that have historically been too small for bond markets and too risky for bank branches — learn to use the CP market properly.
A N100.08 billion oversubscribed issuance is not merely a fundraiser; it is an inflection in the size and type of company that Nigeria's private debt markets can credibly finance. The evidence that an industrial, non-bank business can raise that scale in a single programme — with the market asking for more — resets what Nigerian corporates can plan for. That is exactly what a maturing capital market is supposed to do, and it is happening one landmark issuance at a time.
Up next
Analysis: Nigeria's 23% Rate Cut Is Market Repair, Not Stimulus
Analysis: with inflation down for 12 straight months to 15.39%, the CBN's September cut to 23% is a stabilisation reset, not a demand-side stimulus.
More in Finance
See all
Nigeria FX Defences Firm At 55bn Reserves And 115 Oil
Nigeria holds about 55 billion dollars in gross reserves with a record 46 billion net position as Bonny Light trades near 115 dollars per barrel.

Nigerias Top Firms Lift Nine-Month Profits To N12.1tn
Twenty-two large Nigerian listed companies reported N12.1tn nine-month pre-tax profit, up 35.4 percent on the year as banks and cement groups led delivery.

Access Holdings Profit Rebounds To N667.4 Billion
Access Holdings posts N667.4bn nine-month pre-tax profit as Q3 earnings rebound 78.4%, leading Nigerian bank earnings season delivery.
About the author
Musa Abdullahi
Finance Correspondent
Musa Abdullahi writes for BusinessPress.
More by Musa Abdullahi


