MobiBank Names Strategic Partner and Shareholder for Nigerian Launch
MobiBank has added a strategic partner and minority shareholder in Nigeria, its first African implementation market, while naming ten priority markets and confirming the group keeps technology, brand and control.
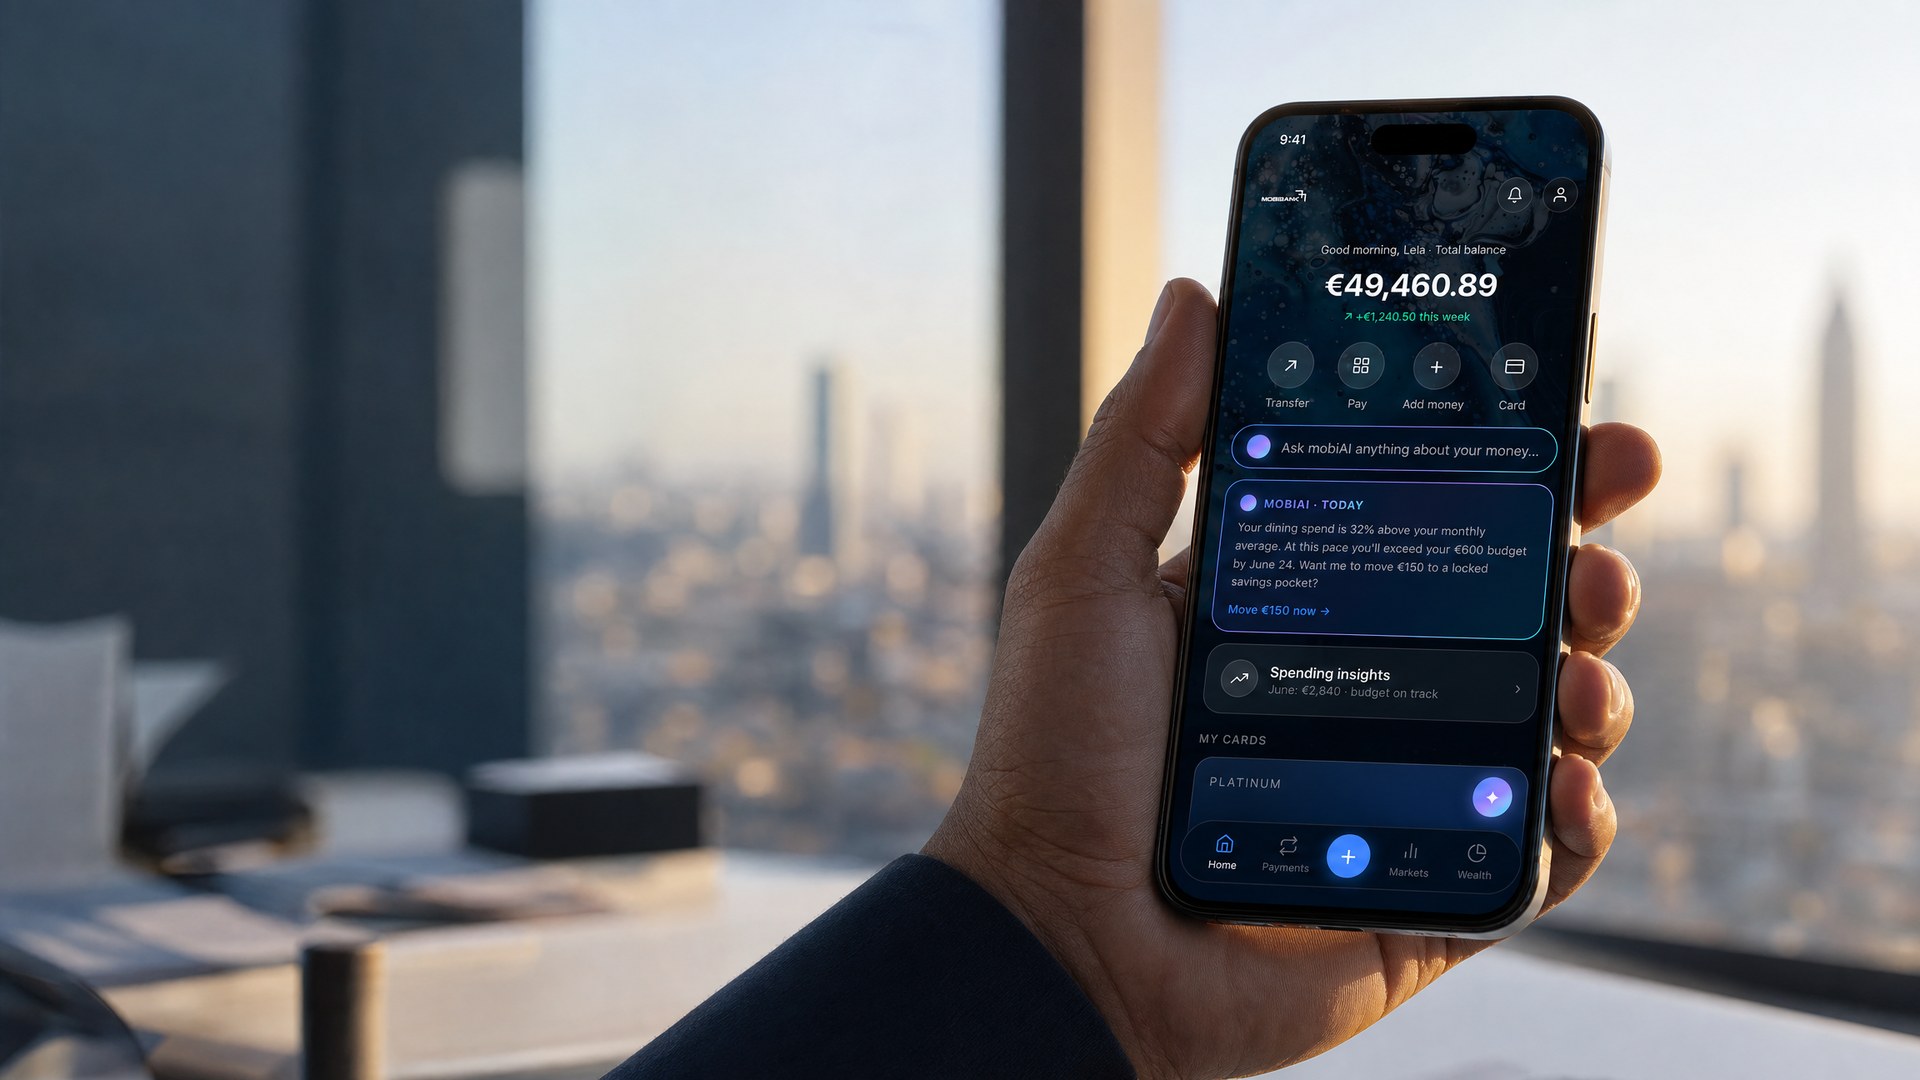
MobiBank, the Helsinki-based financial technology group, has selected a new strategic partner and shareholder for its Nigerian operation, with the partner signing an investment agreement to acquire a minority stake ahead of the company's launch in Africa.
The announcement, made in Helsinki on October 19, 2026, states that MobiBank will retain clear majority ownership of the Nigerian company together with its core technology, intellectual property, brand and strategic direction. Nigeria is being developed as the group's first major African operating market, and MobiBank says market launch remains subject to applicable licensing, regulatory approvals and operational readiness. The company also states that it does not currently hold a banking licence in Nigeria and is not authorised to provide regulated financial services there.
MobiBank has selected ten African priority markets, with strategic partner and market-entry negotiations already under way in several of them: South Africa, Egypt, Nigeria, Algeria, Morocco, Angola, Kenya, Ghana, Ethiopia and the Democratic Republic of the Congo. Nigeria, a market of more than 230 million people, is the first implementation of a partner-led expansion model in which the Finnish group supplies the platform, technology, brand and operating framework, while the local partner contributes investment, market knowledge, distribution networks and support for the licensing process.
What the announcement does not disclose
The partner is unnamed and the size of the investment is not stated, and those two omissions define the current state of the transaction. A minority stake without a published percentage leaves open everything that matters commercially: how much capital is actually committed, what governance rights the local partner receives, and whether the stake comes with exclusivity. MobiBank's own framing is that the partner will provide "significant investment and local execution capability" while the group keeps strategic control, which is a coherent description of a structure that keeps the technology and the licence application in Finnish hands.
The absence of a licence is the more important fact in the announcement, and the company is unusually direct about it. Nigeria's financial sector runs on approvals that cannot be compressed: a banking licence requires capital adequacy, audited financials, a fit-and-proper board, fit-and-proper management, and years of regulatory engagement, while any fintech that touches deposits or payment initiation runs into money laundering, consumer protection and data obligations on top. A company that entered Nigeria with a licence already in hand would be an unusual exception to that sequence. MobiBank's launch language is consistent with a business that expects to be assessed on the same terms as everyone else.
Why partner-led is the right structure for this market
The model is a response to a real constraint rather than a financial engineering preference. A foreign fintech group entering a market of more than 230 million people faces three scarce resources at once: regulatory standing, distribution and local credit knowledge. Building all three from Helsinki is slow and expensive, and the alternative, an outright acquisition of a licensed local institution, prices every one of them into the purchase price and puts regulatory approval at the centre of the deal.
The partner-led structure splits the problem. The local partner brings the relationship with the regulator, an existing customer base, agent networks and the working knowledge of how payments are actually made in the country, which is not the same thing as how they are made in Nordic markets. The foreign group brings the platform, the intellectual property and the processing infrastructure. That is the same logic used by payment firms that enter new markets through local sponsors, and the reason it tends to work better than a greenfield licence application is that the regulator is assessing a company with an operating history rather than a promise.
The Nigerian arrangement is also a continuation. MobiBank announced on September 21, 2026 that the principal partnership agreement establishing MobiBank Africa had been signed with a local partner and members of the local management team, with a financial commitment attached and Nigerian bank accounts already opened. The October announcement adds a shareholder and an investment agreement on top of that structure. The distinction is worth noting: a partner who has signed a principal agreement and committed funds is in a different category from an investor who has only expressed interest, and the October announcement is the first of the two that moves capital.
What has to happen before a Nigerian customer sees the product
Four things stand between this structure and a launch. The first is the licensing pathway itself, and the practical question is which licence the business is pursuing, because a payments or lending licence requires a different regulatory posture from a full banking licence, and the choice determines the capital and governance obligations that follow. The second is the local capital position: a Nigerian-regulated lender or deposit-taker needs local capital and local liquidity, and the partner's committed funds have to be structured to meet that requirement rather than to fund operating expenses.
The third is the compliance build, which is where the fintech licence applications that stall usually fail. Know-your-customer systems tied to the Nigerian Identity Management system, transaction monitoring for the anti-money-laundering regime, and consumer protection for a product sold to a market with high account dormancy are engineering and operating problems as much as regulatory ones. The fourth is distribution economics: the partner's networks have to produce transaction volumes at a unit cost the platform can absorb, which is the test every mobile money and agent network in Africa has had to pass.
Reading the ten-market map
The ten-market list is a useful map of ambition rather than of delivery. It spans North Africa, West Africa, East Africa and Central Africa, with different licensing regimes, payment habits and levels of bank account penetration in each, and MobiBank is explicit in its own announcements that selection as a priority market and the existence of negotiations do not constitute a completed agreement. Only Nigeria is described as having a signed principal agreement, and only Nigeria has a named implementation timetable, which is still described only as disciplined execution, regulatory progress and preparation for launch.
The chief executive, Jussi Teeriaho, said the selection of the partner and shareholder is "an important step toward launching MobiBank in Nigeria" and that the group's "immediate focus is disciplined execution, regulatory progress and preparation for launch". Both claims are consistent with the announcement's contents. What the announcement does not yet contain is the part that would let anyone judge the transaction: a named partner, a stake, a licence application reference or a launch date. For a company whose proposition to Nigerian investors is a locally anchored operating company with foreign capital and technology, the disclosures that would establish that are still to come.
Up next
House Gives MTN, Airtel, Glo Seven Days to Face Panel Over Poor Network Quality
An ad hoc House committee set an October 28 hearing after operators ignored earlier invitations, directing the NCC to ensure compliance and warning that absent chief executives could face arrest summons.
More in Technology
See all
EBRD Backs Beacon Power Services With $20.9 Million for Smart Metering Push
The European Bank for Reconstruction and Development agreed a $20.9 million project financing with Beacon Power Services to deploy smart meters across six Nigerian distribution companies.
NIBSS Builds National Payment Stack on Open-Source Technology
NIBSS has built its National Payment Stack on Transactility's open-source jPOS technology, gaining full source-code control of Nigeria's instant payments platform.
House of Representatives Passes Drone Industrialisation Bill at Second Reading
A bill sponsored by the Deputy Speaker and 12 lawmakers would create a National Drone Industrialisation Council, require a national drone policy within 12 months and offer duty concessions, research credits and accelerated capital allowances to local manufacturers.
About the author
Chinedu Nwosu
Technology Editor
Chinedu Nwosu writes for BusinessPress.
More by Chinedu Nwosu