
Egypt’s enza Raises $6m to Scale Bank-Payment Rails Across Africa
The 4DX-led round with BII, Quona and Algebra will push the payments-infrastructure platform into new markets and licence territories beyond its twelve-country base.
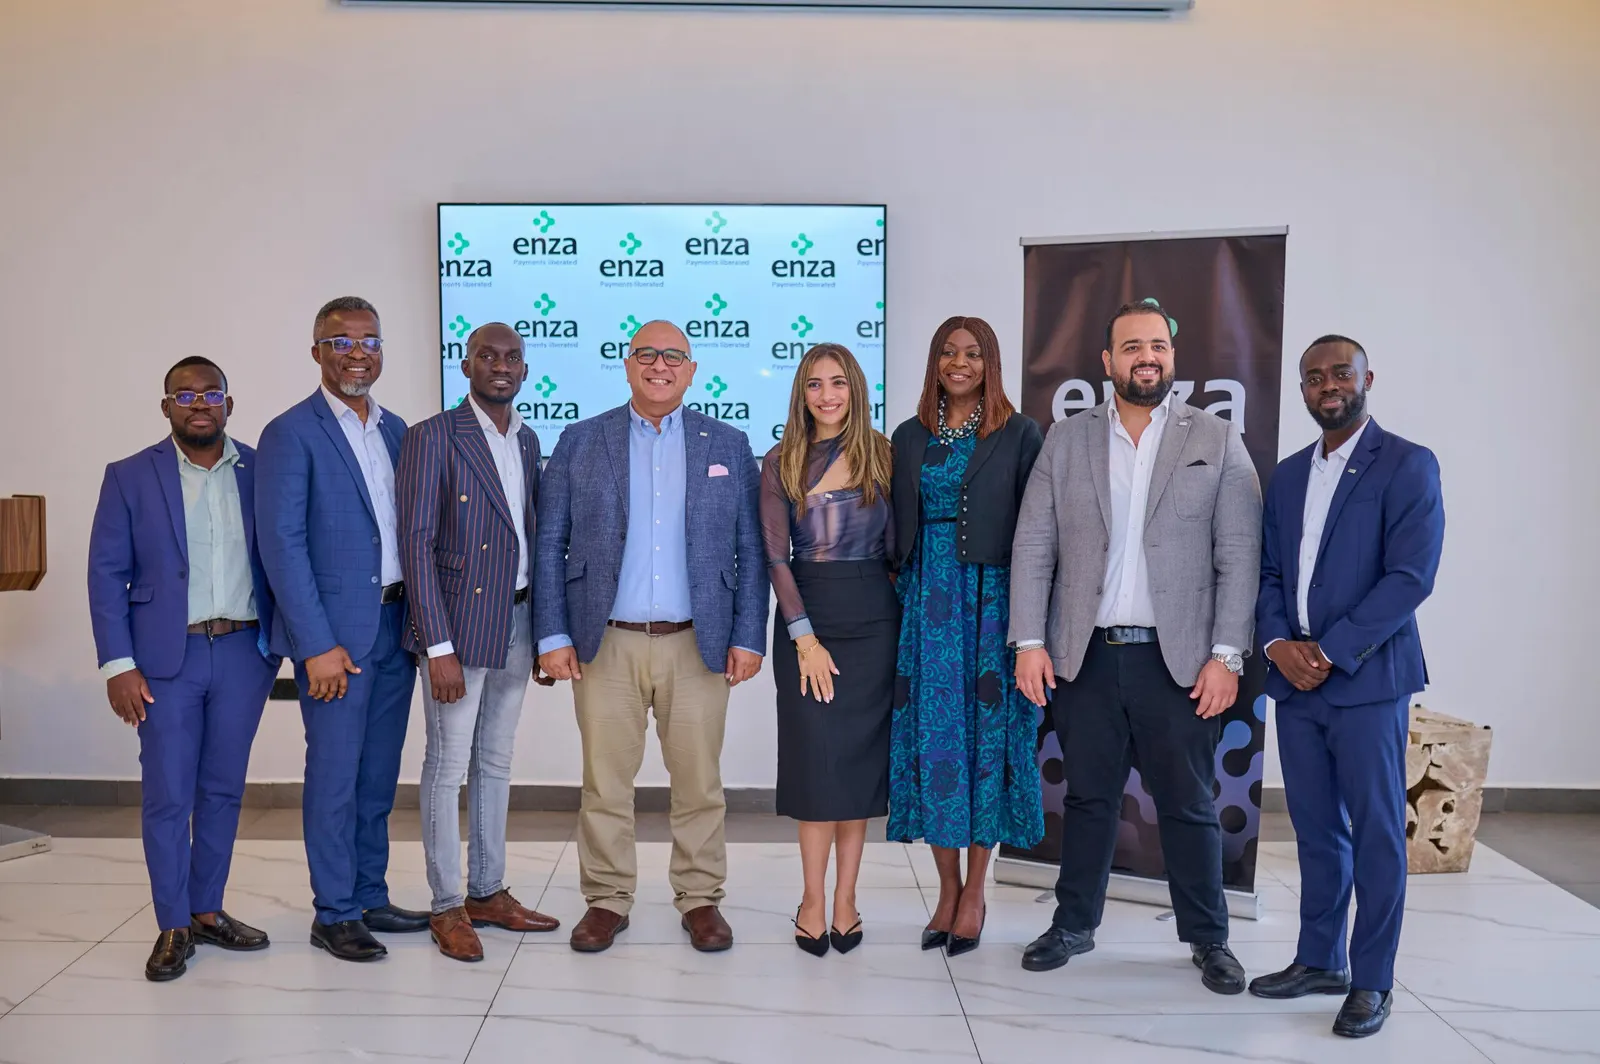
Egyptian payments-infrastructure startup enza has raised $6 million in a Seed+ round led by 4DX Ventures, with British International Investment joining as a new investor alongside returning backers Quona Capital and Algebra Ventures, in a raise the company says will take its bank-payment rails into new markets and licence territories across Africa.
Founded in 2023 by Hany Fekry and Hussein El-Maghribi, enza sells the hard-to-build layer between banks and payments: its single-integration platform lets a bank or fintech in any of twelve current markets launch card issuing, collections, disbursements or savings products without building each market's local rail assembly from scratch. The company raised a $6.75 million seed round in March 2025 co-led by Quona and Algebra; this multiple-product, multi-market raise is the vote that model has a path through the capital-markets cycle.
The pitch: banks want payments infrastructure bought, not built
The underlying economics of the business are what make the raise interesting beyond its size. Africa's banking sector has been acquiring licensed fintechs for payments capability, but the build-versus-buy math has shifted as the regulatory layer has become deeper; enza's platform embeds local schemes, switch-cards, instant-of-sale rails and the compliance packaging into a single integration, targeting the timeline-lag between a bank's decision to launch a product and the physical work of standing it up — historically the longest gap in the African banking build.
Fekry's own framing makes the market validation the raise's centre of gravity: backing from BII and 4DX alongside the seed's returning investors "validates the expansion path", the CEO said, describing proceeds that will be deployed into new markets, additional licences "enabling more banks and fintechs" and an extended product line. A development-finance anchor and a specialist VC bet together suggest the model's unit economics pass the frontier-market financing test — precisely the bar that has limited payments-infrastructure finances across the continent's 2023-2024 correction cycle.
Where the competition is
The infrastructure-banking space is still in its land-grab phase across Africa. Flutterwave, Chipper Cash, Paystack territories (through the Stripe acquisition) and Onafriq control the payments-layer integrations, while nomba, Kora and Imala's newer entrants operate the newer issuing and processing stack — and enza's model, targeting the bank-rails layer rather than the merchant-acceptance layer, positions it inside the least contested architectural slot: bank-side integration that enables everything downstream.
With that slot, though, comes the hardest sales cycle in the market. Enza's twelve-country footprint is already unusually broad for a company at this stage (the team operates in East, West and Central Africa), and the latest capital will be tied up in the cost of the licence register itself — each market requiring central-bank documentation, compliance staffing and settlement-capital buffers that are priced in local currency. That is why BII's participation matters: development finance institutions underwrite precisely the regulatory-capital layer young Nigerian, Kenyan and Egyptian fintechs struggle to fund commercially.
What it says about Africa's payments-investment cycle
The raise lands inside a market that has been in a severe funding slump: Nigeria's startups alone raised only $11.3 million across nine deals in September, a 96.9 per cent drop from August's $364.1 million, per Africa-focused funding trackers. Against that picture, enza's $6 million from African and international strategics says something specific: payments-infrastructure — the ridesharing layer of any financial market's economy — is the vertical that holds institutional financing through the cycle, precisely because its customers' demand (bank engagement) does not depend on retail consumer activity but on the banks' own product roadmaps.
For the Egyptian ecosystem specifically the signal is bigger. Cairo's fintech scene has been sourcing seed-stage capital more productively (Fawry's, Paymob's and MNT-Halan's scale-ups have drawn international capital) but has lacked the seed-to-A-stage infrastructure bets that the Nigerian and Kenyan markets dominate. enza's round — led by a New York-headquartered fund and a UK development institution, with Egyptian and pan-African follow-through — puts Cairo on the map as a place where payments infrastructure for the whole of Africa can be built, not just served.
The execution challenge 2027 will test
The next 12 months decide whether enza's twelve-market model scales or fragments. Each new licence market requires the real deal: local scheme memberships, switch-cards, instant-of-sale rails and the compliance pricing enza's integration model consumes. The company's go-to-market bet is that a single integration removes the marginal cost of each additional market — the flywheel that would let its $6 million carry it a further five or six markets before the series-A clock starts.
The model's ultimate prize is what infrastructure businesses deliver: recurring, transaction-linked revenue that grows with the underlying economy regardless of the venture cycle. If enza's bank clients in twelve markets deepen their product adoption through 2027, the follow-on capital story takes care of itself — and the African payments-infrastructure map gains a market-wide backbone built by one of the newest teams in the sector.
Up next
Analysis: China’s Two-Speed Inflation Is the World’s Next Supply-Side Risk
Factory-gate prices rose 5.7 per cent while consumer prices cooled to 0.7 per cent - a margin squeeze that ends in pass-through, price wars or capacity cuts.
More in Business
See all
IFC Backs 15 African Agritech Startups in New Equity Model
IFC launched an agritech financing programme injecting equity into 15 African startups and linking them to 200 banks via guarantees.

Quidax Targets Banks and Asset Managers as Stablecoins Reshape Nigeria Financial Services
Quidax is pivoting to serve banks and asset managers as stablecoins become a core settlement rail for Nigeria's dollar payments and savings.

Nigeria Startups Raise 635m As Access Drive Begins
Nigerian startups raised 635 million dollars in nine months as Magna Collective organised an investor connection drive pairing 26 founders with 16 funds.
About the author
Amaka Obi
Senior Business Reporter
Amaka Obi writes for BusinessPress.
More by Amaka Obi


