
Nigerian Oil Companies’ Revenue Jumps 58.6% to N11.81trn — but Profits Barely Follow
Seven listed producers grew nine-month revenue sharply on strong crude prices, with acquisition charges and finance costs absorbing most of the gains before they reached the bottom line.
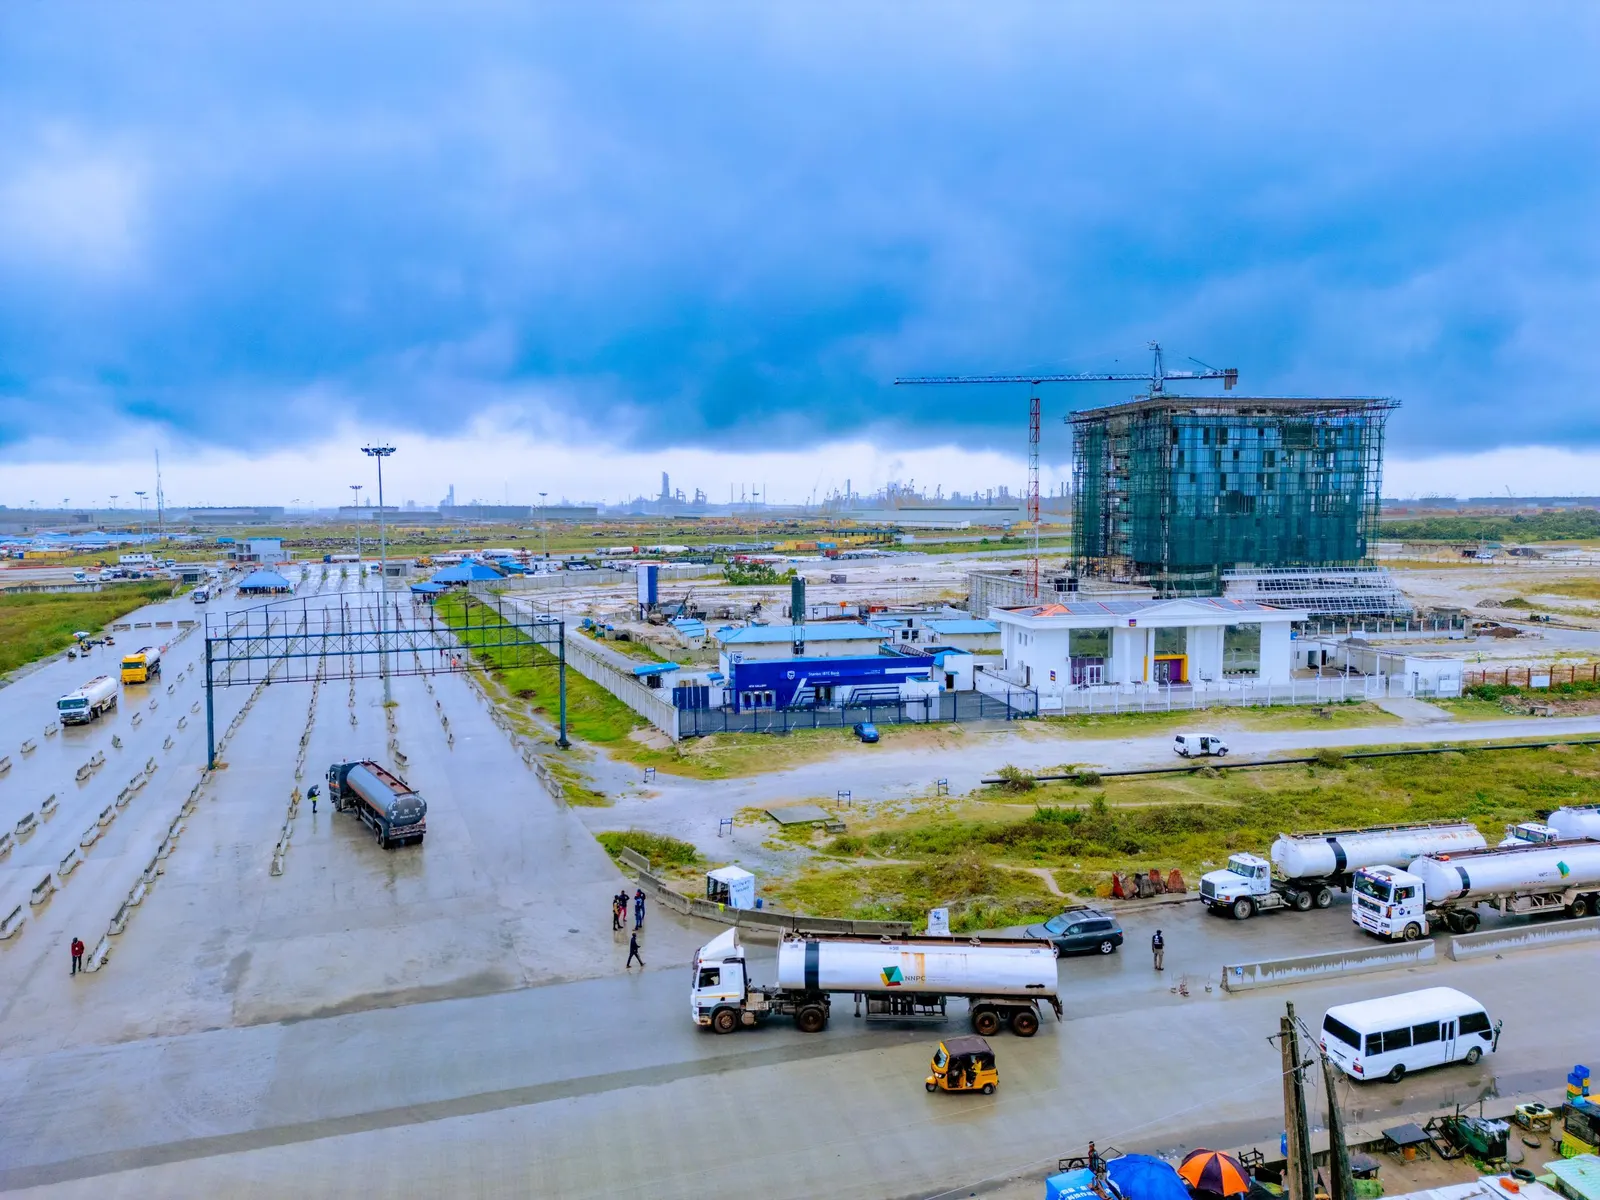
Seven listed Nigerian oil and gas companies grew combined revenue 58.6 per cent to N11.81 trillion in the nine months ended September 30, 2026 — and converted strikingly little of it into profit growth, with acquisition charges and finance costs absorbing the gains, according to sector results data reported by Proshare.
The revenue-performance gap is the season's most instructive sector story. Nigerian energy producers sold barrels and gas into a market where Bonny Light averaged far above prior-year levels, and naira revenue surged accordingly; yet the aggregate profit line barely kept pace, because the costs of growing — acquisition-related charges, debt service on expansion capital and the operational burden of security and logistics — grew faster than operating leverage could offset.
Buying growth with borrowed money
The mechanics of the profit-conversion problem are visible in the sector's deal-making. Nigeria's producing landscape has consolidated in recent years: international oil company divestments flowed to indigenous acquirers who financed their purchases against future cash flow. That strategy books the acquired barrels immediately in revenue, but the acquisition amortisation and the interest bills arrive on the same income statement — and in a high-rate, volatile-oil environment, they arrive hard.
The nine-month results show the equilibrium the model reaches when prices are strong: revenue up 58.6 per cent, profits up but diluted, and balance sheets working through the acquisition debt. The model is not broken — but it is a bet on oil staying high and rates cooperating, which is a different risk profile from the dividend-stable majors the sector replaced.
What the oil price did to the season
The reporting period captured the year's oil-price whipsaw from the producers' side. Brent has swung from more than $119 to the high $90s in a matter of weeks — it settled Friday at $98.32 after the steepest weekly slide of the autumn — and every dollar moves revenue, tax and hedging outcomes for companies whose cost bases are largely fixed. The revenue surge locks in the strong quarters; the softening close of the period pressures the fourth.
Operations added the usual Nigerian haircuts: production recovered toward the 1.6-1.8 million barrel national range, but pipeline deferrals valued at $2.97 billion in 2025 show how quickly uptime, not price, becomes the binding constraint on the sector's revenue line.
The investment read
For equity investors, the sector's season demands a distinction the aggregate numbers blur. Companies whose growth is organic — production uplifts, new wells, debottlenecking — convert price strength into profit with little friction; companies whose growth is acquired convert it first into revenue, then into debt service, with the profit residue arriving later. The nine-month filings sort the two groups, and the market's week of selling punished the second more than the first.
The currency dimension deserves its own line: naira-denominated revenue records flatter the sector's growth against a naira that strengthened 6.26 per cent over twelve months. Dollar-based analysis of the same companies would show more modest expansion — a calibration investors should apply before annualising the 58.6 per cent.
What converts next year
Valuation follows the same distinction. Revenue growth of 58.6 per cent against weak profit conversion typically compresses price-to-earnings multiples, and the sector's shares have spent the season cheapening accordingly; the re-rating trigger is visible in the filings themselves — deleveraging that shows up as falling finance costs, and uptime that shows up as stable production guidance. Both are measurable quarter by quarter, which is what makes the sector's next results the verdict on this season's growth.
The sector's profit-conversion question has a known answer: deleveraging plus uptime. Acquirers that refinance at lower rates as the rate cycle turns, and operators that hold pipeline deferrals down through security investment, keep more of every strong-oil-quarter they earn. The nine-month season showed Nigerian energy's top line is world-class again; the next two reporting seasons will show whether its bottom line has caught up.
Up next
October CPI Arrives Without a Year Rate as December Hike Odds Hit 76%
The last inflation print before the Fed meets publishes no year-on-year headline because of the shutdown data gap, leaving monthly moves to settle a 76 per cent hike market.
More in Business
See all
Oando Holds Production Near 43,000 Barrels Daily
Oando produced 42,985 barrels of oil equivalent per day and grew nine-month revenue 9 percent, confirming its acquired Nigerian assets are operating at run-rate.

MTN Ghana Grows Service Revenue 33.5 Percent
MTN Ghana grew nine-month service revenue 33.5 percent to GHS23.2 billion with EBITDA up 40.6 percent and the margin reaching 61.5 percent as data and fintech drove growth.

NGX Group's nine-month profit before tax climbs 83.3 per cent to N20.6 billion as digital trading lifts the exchange
NGX Group, the parent of the Nigerian Exchange, reported nine-month 2026 results with profit before tax of N20.6 billion, up 83.3 per cent year on year, and profit after tax of N14.7 billion, up 86.4 per cent, in filings published on 27 October.
About the author
Amaka Obi
Senior Business Reporter
Amaka Obi writes for BusinessPress.


