French Bonds Rally After Moody’s Affirmation While Asia Opens Cautiously Ahead of Fed Week
Global markets steadied on Monday, October 26, as French government bonds rallied after Moody’s affirmed France’s rating and the OAT-Bund spread narrowed to 160 basis points, while Asian equities opened cautiously as oil eased from six-month highs.
Global equity and bond markets entered Monday, October 26, 2026, on a calmer footing after the euro area’s biggest recent stress point eased: Moody’s affirmed France’s sovereign rating, sending French government bonds rallying and narrowing the 10-year OAT-Bund spread to about 160 basis points, down from 174 basis points on Thursday, the IMF-affiliated Global Markets Monitor reported.
Reuters reported that world shares advanced on Monday, with investors focused on a week stacked with central bank meetings — the Federal Reserve among them — and a heavy run of corporate earnings that will test confidence in the AI investment boom. Yet the advance was far from uniform: Asia’s session opened cautiously as Brent crude, though softer on the day, still hovered near six-month peaks after a week in which the US-Iran war had inflated energy risk.
Japanese shares dipped, Korean stocks led regional losses, and Chinese equities finished roughly flat as state-related ETF inflows offset concerns about technology valuations, session summaries assembled from Reuters relay and the Global Markets Monitor showed. A Tokyo-listed Brazilian ETF fell as much as 16%, the sharpest single-market casualty of a weekend in which Luiz Inácio Lula da Silva won a fourth presidential term in Brazil’s runoff.
[irp][irp][irp][irp][irp]
The France Rally That Calmed Europe
France’s benchmark spread narrowing by roughly 14 basis points mattered beyond the Bond doctor’s圈 desk. Paris has spent recent weeks fighting descent narratives as budget wrangling weighed on European risk sentiment, and the affirmation by Moody’s signalled to investors that the rating agencies do not regard the country’s fiscal trajectory as an immediate ratings event. European equity indices — supported by bond tightness and oil diplomacy — were among the session’s steadier performers, leaving the OAT-Bund spread as Europe’s best barometer of calm.
The euro-area calm mattered doubly because it came while the US Treasury market was still digesting last Thursday’s rally and the run-up to the Federal Reserve’s October 28 decision. The Global Markets Monitor flagged that rates volatility is likely to ease after that clearing event, a view whose real test will come with the Wednesday statement and the December rate-path messaging that follows.
Asia Opens Cautiously
Asian trade lacked the euro area’s obvious catalyst. Reuters relay from Sydney described a cautious start as investors positioned for what strategists labelled a “formidable” week for risk — with the Fed’s meeting, a run of mega-cap earnings, and continued war-shipping risk converging. The Nikkei’s dip and losses led by Korea suggested several Asian markets had spent last week’s gains on the currency-strength and tightening-fear front rather than on AI enthusiasm.
Chinese equities were the exception’s half: flat rather than lower, thanks to fresh state-linked ETF inflows that offset reluctance around tech valuations. The pattern will recur if domestic policy support continues to substitute for corporate earnings upgrades as the market’s principal floor, a dynamic several Asia desks have flagged repeatedly this quarter.
Whya Quiet Monday Still Carries Risk
Three cross-currents set the week’s template. Oil, though lower Monday, sits near the top of its 2026 range and can move violently on fresh war news. Central banks will translate their inflation dilemma into balance-sheet and rate maps in the space of days, with the Fed’s Wednesday decision the pivot. And the calendar’s dense earnings slate — anchored by Amazon, Microsoft and Alphabet — will decide whether the AI-investment debate remains constructive or supply the next leg of the selloffs that late October has already retraced.
For Nigerian investors, the most straightforward read is that dollar risk appetite turned constructive Monday, which supports frontier fixed income flows and the naira demand picture, but that the week’s capacity to shock remains intact. The take-away from the session is less the direction of any single market than the fact that Monday’s calm survived the one genuine shock it received — Brazil’s election — without bleeding into global spread value or safe-haven stampedes.
Up next
Naira Recovers to ₦1,331 on NFEM Monday After Friday’s ₦27 Slump
The naira rebounded to about ₦1,331.28 per dollar on the official Nigerian Foreign Exchange Market on Monday, October 26, recovering most of the ₦27.12 loss it suffered over Thursday and Friday, while parallel-market rates ranged around ₦1,370–₦1,385.
More in Markets
See all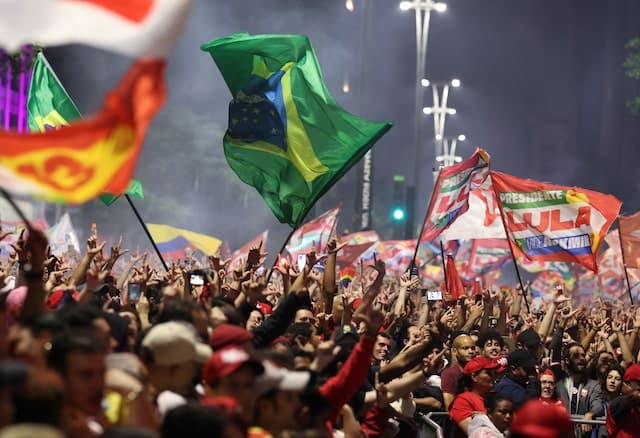
Brazil Stocks and Real Tumble as Lula Wins Fourth Term
Brazil’s Bovespa fell 13.9% on Monday, October 26, in one of its sharpest one-day declines on record, while the real tumbled over 11% intraday before trimming losses to about 8%, after Luiz Inácio Lula da Silva clinched a surprise runoff win for a fourth presidential term.
Wall Street Rebounds Monday as Anthropic IPO Filing Lifts Nasdaq Ahead of Fed Week
US equities snapped a two-day slide on Monday, October 26, with the S&P 500 up 0.70% to 7,676.77, the Dow higher by 0.28% and the Nasdaq up 0.82%, after reports that Anthropic had filed for a Nasdaq IPO under the ticker ANT.
Fidelity Bank shares rise 14.01% in a week as investors re-rate the tier-one lender
Fidelity Bank closed Friday, October 23, 2026 at N24.00 after a 9.09% session gain, taking its weekly advance to 14.01% in a week when the ASI dipped 0.13%, as focus shifted from the recapitalisation narrative.
About the author
Abiodun Abdullahi
Author / Business and Markets Writer
Abiodun Abdullahi writes for BusinessPress.