
Grey Joins Licensed Ranks Of Money Transfer Operators
Grey secured an International Money Transfer Operator licence from the CBN as Nigeria remittance market grows past 100 licensed operators.
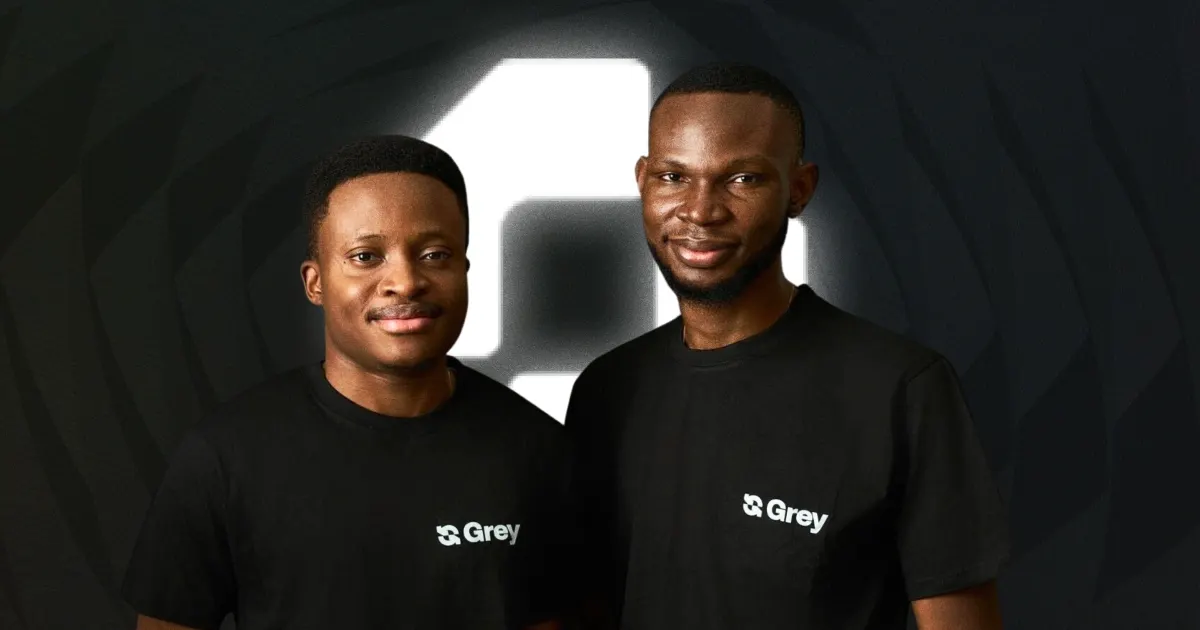
Grey, the Nigerian cross-border payments company, has secured an International Money Transfer Operator licence from the Central Bank of Nigeria, bringing one of the diaspora fintech segment's best-known challengers into the fully licensed tier of a remittance market that has grown from fewer than fifteen operators a decade ago to more than one hundred today.
The licence, reported by technology publication Condia this week, formalises Grey's transition from a technology intermediary that enabled virtual accounts and payment routing for African freelancers and remote workers into a regulated money transfer institution whose remittance corridors operate under the Central Bank's direct supervision. The move joins Grey to the IMTO tier that carries Nigeria's multi-billion-dollar annual remittance flows — the channel through which the diaspora's household support, investment transfers and business payments enter the official economy.
Playing in the market's fastest-compounding flows
Nigeria's remittance base — tens of billions of dollars annually, and among the largest diaspora inflow systems on the continent — has been expanding through both volume and efficiency. Recent data show second-quarter diaspora inflows strengthening, with the average exchange rate of the quarter firming as the Central Bank's channel reforms deepened: new IMTO licenses, transfer product innovations and the operational plumbing that lets recipients receive naira liquidity immediately and at competitive pricing. Every reduction in transfer cost fractionally shifts flows from informal arbitrage into the official market, and addition of licensed competition accelerates exactly that reallocation.
Grey's positioning speaks to the market's underserved stratum: young professionals, freelancers and remote-tech workers earning hard currency who need accounts, virtual banking and payment functionality that legacy money transfer halls never offered. The company's founding proposition — cross-border accounts for Africans earning globally — fits the demographic whose migration and digital earning patterns have redefined the remittance market's product definition from cash pickup to full financial infrastructure.
What the licence changes operationally
An IMTO licence changes a fintech's legal physics. Operating as an unlicensed technology layer, Grey could facilitate but not own the money-movement permissions its users' transfers required, embedding dependence on partner institutions. As a licensed operator, the company controls its remittance corridors' compliance architecture — transaction monitoring, customer due diligence and the reserve and settlement arrangements regulators require of institutions moving the diaspora's funds. The licence also expands what Grey can offer its customers: payout structures, partnerships with local banks and mobile wallets, and the treasury operations whose scale makes transfer pricing competitive.
For the wider fintech sector, the licensing also marks a stage in the Central Bank's regulatory posture: accommodations that let consumer-facing fintechs formalise rather than fragment. Grey's journey resembles a path several Nigerian-born payments companies are travelling — start as an enabling layer, build customer scale, then acquire the licences whose sequential approval converts a tech product into a financial institution. Each successful transition demonstrates that hallway between innovation and regulation remains open in Nigeria's framework.
The competitive market it enters
The IMTO tier has consolidated around a defined set of dominant players — international transfer giants with global corridors and Nigerian banks' own remittance products — but a new generation of Africa-focused digital operators has been challenging the incumbents on pricing, speed and customer experience, with wallet-based providers and fintech entrants now moving remittances for the diaspora segments whose transfer expectations are smartphone-native. The market's pushing force is digitisation at both ends: senders using wallet interfaces in Europe and North America, recipients receiving into bank accounts and mobile wallets without physical collection.
Competition also arrives from the domestic improvements the Central Bank has engineered: licensed payout efficiency, the naira-liquidity access IMTOs receive for settlement and the FX market reforms that give licensed operators rate visibility rather than arbitrage opacity. In that configuration, a licensed challenger's edge is product depth — banking-style functionality layered on transfers — rather than rate undercutting alone.
What it means for the diaspora economy
For the Nigerian diaspora — whose transfers fund family support, property investment, local business operations and social infrastructure projects — expanded licensed competition is a direct pocketbook matter. Transfer pricing in Nigeria's corridors has historically run well above the global average cost of remitting money; competition among licensed IMTOs, fintechs and banks is the mechanism that pushes costs toward the intervals the corridors' efficiency should produce. Every 100 basis points saved on a remitted dollar is local purchasing power the diaspora economy retains across millions of transactions annually.
The licence also strengthens Nigeria's remittance-data architecture: formalised channels mean flows measured, taxed correctly where applicable and counted in the official external accounts whose strength the currency market's stability depends on. As Nigeria continues courting its global citizens' capital — diaspora bonds, property schemes and investment products targeting diaspora savings — the licensed transfer infrastructure is the base layer those instruments rely on.
Grey's move from virtual banking upstart to licensed money transfer operator is one of the quiet confirmations Nigerian fintech offers about its maturation: the path to scale now runs through regulation, not around it. How the company converts its licence into market share against incumbents with size advantages — and whether the diaspora's underbanked segments find its product economics compelling enough to move — will be judged by the flows that follow over the next reporting cycle.
Up next
Customs Enlists Six Agencies Against Trade Crimes
Nigeria Customs Service engaged six federal agencies in a coordinated framework against cross-border financial crimes and trade-based money laundering.
More in Technology
See allEBANX launches OPay Direct Debit recurring payments in Nigeria
EBANX has become the first global payments company to launch recurring payments through OPay Direct Debit, giving merchants access to about 40 million monthly active users.
MobiBank Names Strategic Partner and Shareholder for Nigerian Launch
MobiBank has added a strategic partner and minority shareholder in Nigeria, its first African implementation market, while naming ten priority markets and confirming the group keeps technology, brand and control.
Baxi Exit Shows Nigeria's Offline Agent Banking Model Under Stress
Onafriq's wind-down of Baxi highlights a broader unit-economics crisis in Nigeria's offline agent banking model as inflation, costs and instant digital payments squeeze the business that once brought millions into the financial system.
About the author
Chinedu Nwosu
Technology Editor
Chinedu Nwosu writes for BusinessPress.
More by Chinedu Nwosu


