Indonesia Stocks Plunge 11% as MSCI Proposes Emerging-Market Downgrade
The Jakarta Composite fell 11.57 per cent, its heaviest one-day drop since 1998, after MSCI said Indonesia could no longer be classed an emerging market and proposed standalone status that would push it out of global benchmark indexes.
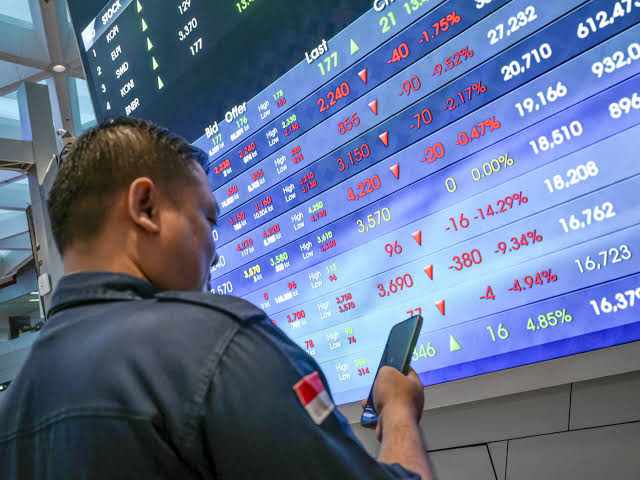
Indonesian shares plunged more than 11 per cent on Friday, the heaviest single-day fall since 1998, after index compiler MSCI said it was no longer appropriate to keep the country classified as an emerging market and proposed moving it to "standalone" status — a step that would remove it from the world's main equity benchmarks.
The Jakarta Composite Index fell 8 per cent at the open, triggering a trading halt. When it resumed, the index was down 11.1 per cent, trading at its lowest level since 2020. By the close the gauge had shed 11.57 per cent to 5,185.10, according to exchange data.
The announcement, which came outside MSCI's regular review calendar, blindsided investors and Indonesian officials and triggered the largest one-day equity decline in about 28 years.
A two-tier downgrade, not a step down
Ordinarily, an emerging-market downgrade would push a country toward frontier status. MSCI's proposal skips that rung entirely, placing Indonesia in a standalone category alongside markets such as Jamaica, Panama and Palestine, outside the index provider's main global groupings.
The distinction matters enormously for capital flows. Trillions of dollars of passive and benchmarked funds track MSCI's emerging-market indexes. A move to standalone status would force those funds, or those measured against the indexes, to sell their Indonesian holdings — an automatic, rule-driven outflow rather than a discretionary one.
MSCI said significant concerns remain around market dysfunction and that Indonesia's continued classification as an emerging market was "no longer appropriate." It added that it expects to proceed with the reclassification unless the consultation identifies clear evidence of material improvements in market governance and functioning.
Why MSCI acted
The concerns MSCI has flagged are not new. They centre on investability: opacity in shareholding structures, allegations of coordinated trading behaviour, and a perceived failure of enforcement to produce meaningful results. MSCI froze Indonesia in its indexes in January 2026 and had already warned of a possible downgrade, setting a November review as the deadline for visible reform.
Authorities in Jakarta said in April that reforms were complete. MSCI's decision to launch the consultation before the regular November review — and weeks before the scheduled index announcement — suggests the regulator found those steps insufficient. The Indonesia Stock Exchange has said it will seek clarification from MSCI on the basis for the proposal.
The consultation will remain open until 30 April 2027, with a final decision due by the end of June 2027. In the meantime, MSCI will freeze changes including increases to Foreign Inclusion Factors and additions of new constituents to the MSCI Indonesia Investable Market Index.
The passive-funding problem
The market pain is driven less by the decision itself than by what it implies for foreign capital. Global funds have already pulled a net $4.9 billion from Indonesia's stock market this year, on track for the benchmark's worst year on record, with the index down about 39 per cent since January. The rupiah has lost roughly 8 per cent over the same period.
With the downgrade risk now formalised, the pressure could intensify: investors who were waiting for clarity may act before the outflows become forced, and the drag on the currency could strengthen if dollar demand rises to fund exits.
Read-across for other markets
The episode is a sharp reminder that index classification is a governance judgement, not merely a market-size one. Countries that fail on investability and transparency risk losing access to passive capital even when their economies are large and growing.
For other emerging and frontier markets, the immediate lesson is that index position can be reversed quickly. South Africa, Nigeria and other African markets that have worked to attract benchmarked flows face the same underlying test: that inclusion depends on rules being visible, enforced and credible to outside investors.
Indonesia's exchange now has until April 2027 to demonstrate those conditions. Whether it can will determine not only the fate of its own market, but the willingness of other countries to assume that reform commitments hold.
Up next
Nigeria's Eurobond Yields Fall as Global Bond Rally Lifts Prices
The three-year yield dropped 23 basis points to 6.45 per cent and the ten-year fell four basis points to 7.93 per cent as a record one-day rally in US Treasuries and a softer dollar lifted Nigerian dollar debt, with a $1.5 billion bond due in November 2027 in focus.
More in Markets
See all
Naira Holds Near N1,331 as Parallel-Market Gap Narrows to 2.88 per Cent
The official NFEM rate firmed to N1,331.61 to the dollar while street quotes sat around N1,375 to N1,390, leaving a spread that has compressed sharply as reserves climb and central bank FX sales stay low.
Dollar Set for First Weekly Drop in Five Weeks as AI Jitters Cut Yields6th
The dollar index held near 102.07 and headed for its first weekly decline since mid-September as the 10-year Treasury yield fell about 15 basis points and the euro recovered from a 17-month low.
Gold Rebounds to Two-Week High but Still Heads for a Weekly Loss
Spot gold rose about 0.4 per cent to near $4,187 an ounce, helped by a softer dollar and a sharp fall in Treasury yields, even as hot US producer prices kept Fed rate-hike bets alive and capped the metal near $4,235.
About the author
Adaeze Okonkwo
Markets Editor
Adaeze Okonkwo writes for BusinessPress.
More by Adaeze Okonkwo