
Nigeria Money Supply Approaches The 100tn Mark
Nigeria broad money supply has climbed to N99.23 trillion despite CBN tightening, reviving inflation and naira concerns ahead of the December MPC.
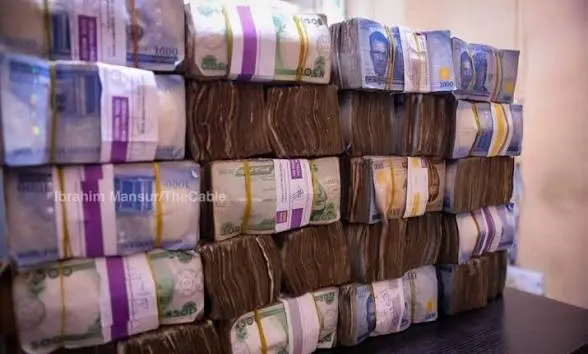
Nigeria's broad money supply has climbed to N99.23 trillion — approaching the N100 trillion threshold just as economists and rating specialists flag renewed inflation and currency concerns — a money-stock milestone that frames the monetary policy conversation heading into the December MPC session, where the arithmetic between liquidity, prices and the naira's stability gets its year-end test.
The figure, published through BusinessDay's monetary reporting this week, shows the broadest measure of money — currency, deposits and their near-money extensions — expanding despite the Central Bank's sustained tightening programme, whose open market operations have sterilised successive trillions of excess liquidity through 2026. Analysts attribute the increase significantly to expanded government revenue circulating through the system — higher crude prices lifting FAAC distributions whose spending feeds bank deposits — alongside the improved oil-sector performance whose foreign-exchange and fiscal effects ripple through the money stock's base.
What M3 near N100 trillion measures
The money supply is the economy's total spending power inventory, and its growth rate is the medium through which monetary policy operates. M3 near N100 trillion in an economy whose price level has doubled since 2023's devaluations is not intrinsically alarming — the nominal money stock rises with transaction volumes, price levels and financial deepening — but the pace matters: when broad money grows faster than real output's nominal expansion, the excess is either absorbed in bank deposits (whose velocity decides its inflation risk) or transmits into prices and the exchange rate. The Central Bank's liquidity management exists precisely to keep that margin narrow.
The composition of the growth clarifies the risk profile. Government-funded liquidity — FAAC-driven allocations whose spending expands deposits at state and federal levels — creates money that chases the economy's goods, contracts and imports; private credit growth, by contrast, creates purchasing power whose productivity use potentially grows the economy's capacity. The current M3 expansion's tilt toward government-driven deposit expansion is the feature the monetary economists flag: liquidity whose supply the fiscal accounts generate and whose absorption the real economy must reprice.
The tightening programme's counterweight
The Central Bank's open market operations have been the M3 conversation's other half. The OMO bill programmes — whose issuance has sterilised the excess liquidity the fiscal inflows generate — have priced short rates at levels that make holding central bank paper competitively attractive, pulling deposits from circulation into sterilised instruments. Each mop-up operation's volume and yield is the regulator's countermeasure to the money-stock arithmetic whose expansion the fiscal side drives, and the moderating OMO intensity into November — the dealers association's projected liquidity calendar mirrors it — signals a reckoning whose inflation consequences the MPC must weigh.
The policy committee's December meeting, arriving as the year-end liquidity season whose festive-quarter cash demand and FAAC arithmetic complicate the picture, will set the closing stance for the year. The market's expectation structure — rate path prices, OMO yield assumptions and the money-market curve — has been built on the disinflation campaign's continuation; the M milestone forces the committee's explicit reconciliation between the growth-supporting liquidity and the price-stability mandate whose credibility the year's success has funded.
Where the money could go: inflation or investment
The economy's absorption of M3 growth determines whether the milestone becomes an inflation worry or a growth asset. Nigeria's real economy has record demand for finance: manufacturers whose working capital needs the rate environment has squeezed, the SME sector whose credit access the intervention programmes were built for, infrastructure whose long-term financing the pension and bank systems could deploy. If the system's liquidity channels into that productive demand — through credit growth whose quality the banks' risk processes oversee — the money-stock expansion finances capacity, and its price effects remain controlled.
The pessimistic channel is equally real: liquidity that circulates into import demand, speculative positioning and consumer-price chasing in an economy whose production base remains constrained. The food inflation pressure points whose grain-supply arithmetic the 2026/27 harvest has documented, the energy costs whose pass-through continues and the imported-input exposure whose FX conversion requirements are set — each is the inflation channel through which excess liquidity's effects materialise when absorption capacity lags.
The rating and currency implications
Rating agencies and currency markets read money supply as a leading indicator. Broad money growth that outpaces the reserve base and the real economy's nominal expansion pressures the currency's long-run purchasing power — the transmission that the naira consolidation band's defence has been engineered to withstand, and whose credibility the record reserves and the external account's strength provide. The Central Bank's messaging through the M3 milestone's publication has maintained the tightening commitment whose consistency keeps expectations from repricing.
For investors, the milestone refines the asset allocation map. Fixed-income positioning must price the liquidity release whose November calendar the dealers describe — OMO curve compression, the possibility of the rate-easing cycle whose first cuts the markets have begun positioning for — against the inflation risk whose M3 arithmetic the milestone exposes. The money-market's short end, the FX carry structure and the bank-credit spread environment each carry the money-stock question in their pricing, and the December MPC is the event whose resolution the volumes await.
The N99.23 trillion milestone is best read not as a broken red line but as a dashboard item: an economy whose money stock, fiscal liquidity and monetary absorption are running in close sequence, and whose year-end policy session must set the balance. November's inflow arithmetic, the MPC's December stance and the liquidity channels the banks choose will decide whether the milestone becomes the inflation rerun the pessimists price or the growth financing the optimists expect.
Up next
Fidelity Bank Repays 400m Eurobond At Maturity
Fidelity Bank redeemed its 400 million dollar Eurobond at maturity, underscoring the Nigerian banking sector restored external balance-sheet strength.
More in Economy
See all
Nigeria's economy expands for a fourth straight month as the Composite PMI hits 53.0, even as household sentiment slumps
The Central Bank of Nigeria's Composite Purchasing Managers' Index rose to 53.0 in September from 52.7 in August, marking the fourth consecutive month of expansion, while the household expectations survey showed consumer sentiment worsening to minus 18.7 points.

Australian inflation rises to 4.3% as goods and services pressures strengthen
Headline inflation and the underlying trimmed mean both increased in September, according to figures released on 28 October.
Nigeria's Portfolio Investment Rises 45% to $6.51 Billion in Q2 2026
Nigeria's portfolio investment rose 45 per cent to $6.51 billion in the second quarter of 2026, Central Bank data show, with debt securities driving most of the increase as the government courts more foreign capital.
About the author
Amina Suleiman
Finance Correspondent
Amina Suleiman writes for BusinessPress.
More by Amina Suleiman
Nigeria FX Defences Firm At 55bn Reserves And 115 Oil
Finance26 mins ago
33 Million Nigerians Face Food Insecurity By 2027
Agriculture49 mins ago
VFD Group Nine-Month Profit Nearly Doubles
Finance

