First HoldCo shares jump 10% as N911.24 billion pre-tax profit resets valuation
The banking group’s 60.84 per cent profit growth drew fresh buying, narrowing the holding-company discount and lifting sentiment on the NGX.
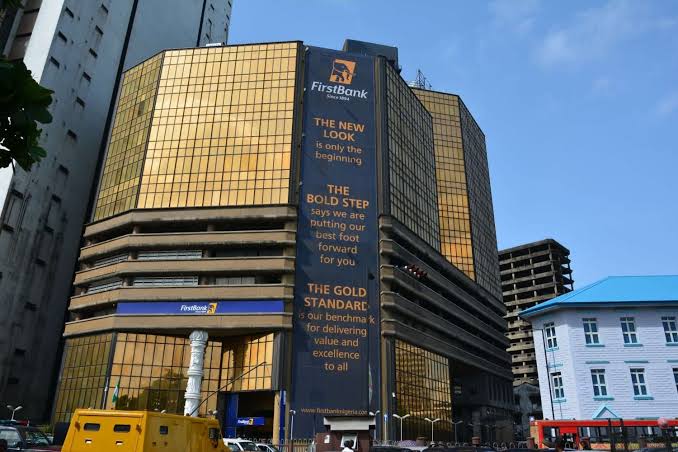
First HoldCo shares rose 10 per cent after the company reported a 60.84 per cent increase in pre-tax profit to N911.24 billion for the first nine months of 2026, a result that reset expectations for Nigeria’s largest banking group. The gain made the stock one of the strongest performers in an otherwise mixed market session.
The holding company, which controls First Bank and a growing set of financial subsidiaries, benefited from higher interest income, improved fee earnings and a lower cost of risk. The result also reflected the gradual consolidation of its recapitalisation and restructuring efforts, which have changed the group’s capital base and business mix.
Investors responded because the profit growth was large enough to change valuation. A 60 per cent increase in pre-tax profit is not a marginal beat. It suggests that the group’s core lending franchise is generating more income than the market had assumed, even as the operating environment remains difficult.
What drove the profit
Nigerian banks have earned more from lending as interest rates remain elevated. First HoldCo’s loan book has repriced faster than its deposit costs, widening the spread between what it earns on assets and what it pays for funding. That dynamic has supported net interest income across the sector.
Fee and commission income has also improved as transaction volumes recover and the group expands its digital and agency banking channels. The contribution is smaller than interest income, but it is more stable and less capital-intensive, which makes it valuable for long-term returns.
Asset quality appears to have held up better than feared. A lower provisioning charge can flatter profit growth, but it also signals that borrowers are servicing their obligations. The group’s exposure to large corporate borrowers and the public sector remains a key risk, particularly if the naira’s recent weakness persists.
The holding-company discount
First HoldCo trades at a discount to the sum of its parts, a common feature of Nigerian holding companies. Investors worry about double leverage, capital allocation and the complexity of managing businesses that range from commercial banking to insurance and asset management.
The share-price gain suggests that some of that discount is closing. If the group can demonstrate consistent profit growth, pay dividends and simplify its structure, the market may be willing to value it more like a diversified financial institution and less like a collection of separate entities.
That re-rating is not automatic. Holding companies must show that they add value through capital allocation, risk management and shared technology rather than simply owning stakes. The market will also want clarity on the dividend policy and the pace of any further restructuring.
Why the market rewarded the stock
The 10 per cent move was partly a relief rally. Banking stocks had been volatile amid concerns about recapitalisation costs, regulatory changes and the effect of a weaker currency on capital adequacy. A strong result from a systemically important group eased some of those fears.
It also reflected positioning. Investors who had been underweight the sector sought exposure to a large, liquid name with a clear earnings surprise. In a market where liquidity is concentrated in a few counters, a single strong result can move prices sharply.
The gain does not mean the risks have disappeared. Banks remain exposed to sovereign risk, inflation and the possibility of higher provisioning if the economy slows. The quality of future earnings will depend on whether the group can sustain margins while growing its loan book prudently.
The longer-term test
First HoldCo’s challenge is to convert a cyclical earnings surge into durable returns. That means growing non-interest income, managing costs, investing in technology and maintaining strong capital buffers. It also means proving that the holding-company structure creates value rather than adding layers of cost.
For investors, the result is a reminder that Nigerian banks can still deliver strong profits when the operating environment cooperates. But the sector’s history shows that earnings can reverse quickly when oil prices fall, the currency weakens or loan losses rise. The current cycle is favorable, but it is still a cycle.
The next test will come with the full-year results and the dividend announcement. If First HoldCo can sustain profit growth and return capital to shareholders without weakening its balance sheet, the re-rating may have further room. If the third-quarter gain proves to be a peak, the market will adjust quickly.
Up next
Naira falls N28 to N1,365 per dollar in sharpest one-day decline since 2025
The official rate weakened 2.1 per cent as dollar demand overwhelmed CBN intervention, reviving concerns about import costs and inflation.
More in Markets
See all
United Capital approves N18 billion dividend after record 2025 profit
Shareholders approved a final 70-kobo payment, taking the full-year distribution to N1 per share after an interim dividend.
NGX turnover hits N15.06 trillion in nine months as market depth improves
Equity turnover crossed N15.06 trillion between January and September 2026, signalling deeper liquidity even as trading stays concentrated in large-cap stocks.
NGX market capitalisation climbs back above N160 trillion as week closes green
Nigerian equities ended the week higher, pushing market value past N160 trillion on banking and industrial gains, though currency risk remains.
About the author
Abiodun Abdullahi
Author / Business and Markets Writer
Abiodun Abdullahi writes for BusinessPress.
More by Abiodun Abdullahi