African central banks raise gold reserves 113% in shift away from dollar assets
Reserve managers are buying bullion to diversify counterparty risk, with consequences for global gold demand, mining revenue and financial sovereignty.
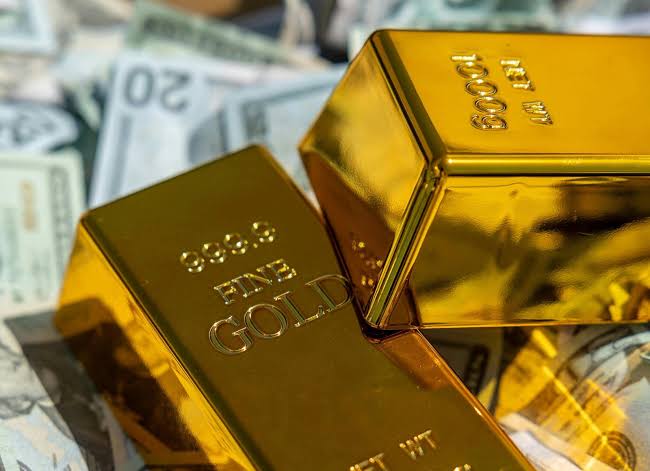
African central banks increased their gold reserves by 113 per cent, according to BusinessDay, as governments reduced their reliance on dollar-denominated assets and sought protection against currency volatility. The shift is part of a broader global trend that has accelerated since sanctions, inflation and geopolitical fragmentation changed the way reserve managers think about safety.
Gold is not a new reserve asset. What is new is the scale and speed of accumulation in Africa. Countries that once held most of their reserves in US Treasury bills and bank deposits are now buying bullion, often domestically or through regional channels, to diversify away from a single currency and counterparty.
The move has implications beyond central bank balance sheets. It affects global gold demand, local mining revenues and the way African governments insure themselves against external shocks. It also signals a subtle shift in financial sovereignty, as countries seek assets that cannot be frozen or devalued by another government’s policy decision.
Why central banks are buying
The dollar remains the dominant reserve currency, but its appeal has been complicated by sanctions and by the Federal Reserve’s interest-rate cycle. When the United States uses the dollar system as a foreign-policy tool, other countries have an incentive to hold assets that are outside that system.
Inflation is another factor. Gold has historically preserved purchasing power over long periods, even though it pays no interest and can be volatile in the short run. For reserve managers worried about the real value of their holdings, a modest allocation to bullion can act as insurance.
African currencies have also been under pressure. The naira, the cedi, the Kenyan shilling and several other currencies have experienced sharp swings in recent years. Holding more gold gives central banks an asset that is priced internationally and can be sold or swapped when foreign exchange is scarce.
The local mining connection
Africa is a major gold producer, and several governments have tried to capture more value from the metal by requiring refiners to process it locally or by buying directly from miners. That policy can support reserves while also building a domestic refining and trading ecosystem.
But the link is not automatic. Gold produced in Africa is often sold through international hubs before it returns as refined bullion. Building a local market requires trusted assayers, secure logistics, transparent pricing and access to financing. Without those, central banks may still prefer to buy from global dealers.
For mining companies, stronger official demand can be positive. It provides a reliable buyer and can reduce the discount they receive for unrefined metal. It also creates an incentive to formalise production and reduce illicit flows, although enforcement remains a challenge.
Reserve adequacy and risk
Gold is not a substitute for liquid foreign exchange. A central bank cannot pay for imports with bullion unless it sells or swaps the metal, which takes time and can move prices. Reserves need a mix of liquid assets, including dollars, euros and high-quality bonds.
The 113 per cent increase should therefore be read as a diversification strategy, not a rejection of the dollar system. Most African central banks still hold the majority of their reserves in foreign currency. Gold is a hedge, not a replacement.
There is also a valuation risk. Gold prices have risen sharply, and buying at high levels can lock in losses if the market corrects. Reserve managers must weigh the insurance benefit against the opportunity cost of holding a non-yielding asset.
What it means for markets
For global gold markets, African demand is small relative to purchases by China, India and other large reserve managers, but it adds to a bullish narrative. Central bank buying has been one of the strongest sources of demand in recent years, and African purchases reinforce that trend.
For African governments, the strategy can improve financial resilience. A larger gold reserve can support confidence in the currency, provide collateral for foreign borrowing and serve as a last-resort source of foreign exchange. Those benefits are real, especially for countries with limited access to international capital markets.
The risk is that gold accumulation becomes a substitute for deeper reforms. Reserves cannot fix a weak export base, a large fiscal deficit or poor governance. They can buy time, but they cannot create sustainable growth.
The longer view
The shift toward gold reflects a world in which reserve managers trust fewer institutions and want more control over their assets. That trend is likely to continue as geopolitical competition intensifies and sanctions become more common.
For Nigeria and its peers, the lesson is to build a diversified reserve portfolio while maintaining the liquidity needed to manage the currency. Gold can play a role, but it should be part of a broader strategy that includes export diversification, fiscal discipline and credible monetary policy.
The 113 per cent increase is a significant number. It shows that African central banks are no longer passive holders of foreign paper. They are active managers of risk, and they are willing to change the composition of their reserves when the world changes around them.
Up next
NGX market capitalisation crosses N160 trillion as banking stocks rally
Fresh buying in banking and industrial counters lifted the bourse, with improved breadth suggesting the rally is broadening beyond a few stocks.
More in Markets
See all
Global bond investors return to a battered market in search of yield
After steep losses, global bonds are drawing buyers as yields rise, but inflation, fiscal risk and currency volatility keep the recovery fragile.
Guinness Nigeria’s N16 dividend tests cash generation as costs rise
Guinness Nigeria’s N16 payout is attractive for income investors, but sustaining it depends on cash flow, consumer demand and cost control.
CBN bills hit N5.6 trillion, drive 74% of September money-supply growth
A N5.6 trillion stock of CBN bills absorbed most of September’s money-supply increase, highlighting the central bank’s heavy reliance on OMO.
About the author
Abiodun Abdullahi
Author / Business and Markets Writer
Abiodun Abdullahi writes for BusinessPress.
More by Abiodun Abdullahi