Rabiu Tells Economic Summit Firms Should Buy Dollars From the Market, Not CBN Allocations
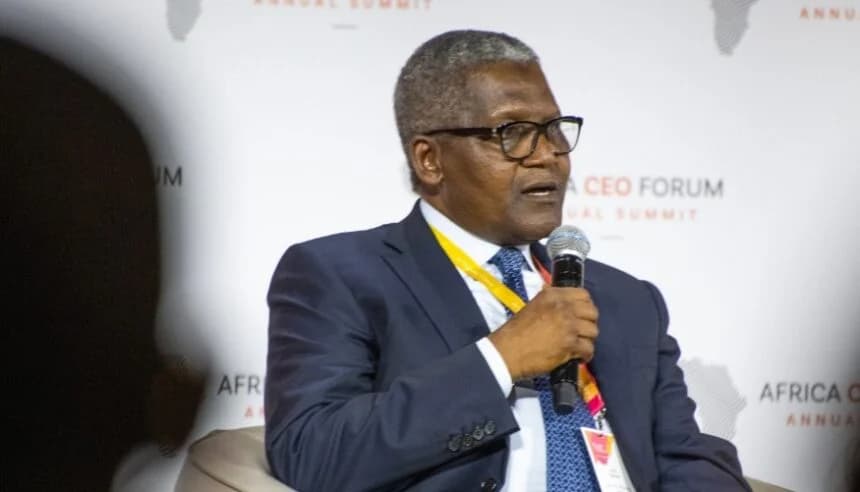
Aliko Dangote, the Dangote Group’s president, told the 32nd Nigerian Economic Summit on Monday, October 26, that companies should buy foreign exchange through the market at prevailing rates instead of depending on direct Central Bank allocations, warning that naira availability alone does not solve machinery import needs.
The chairman of the Dangote Group, Aliko Dangote, told the 32nd Nigerian Economic Summit in Abuja on Monday, October 26, 2026, that Nigerian companies should be able to buy their dollars through the market at prevailing rates instead of depending on direct Central Bank of Nigeria allocations, BusinessDay reported. His warning was pointed: a company can have all the naira it requires and still be unable to obtain foreign exchange for machinery, so access design matters more than currency supply in the aggregate.
The intervention lands at the centre of this year’s most consequential FX question. The reform era unified Nigeria’s exchange windows and moved price discovery to the Nigerian Foreign Exchange Market, where the official rate held near ₦1,331.28 per dollar on Monday after recovering from Friday’s slide. But behind that surface stability, corporate buyers of dollars for capital equipment still navigate allocation queues, documentation requirements and timing frictions that shape capital expenditure decisions far more than the fixing itself does.
Dangote’s group is uniquely credible on the point. The Dangote Petroleum Refinery — which drew the country’s largest industrial machinery import programme in a generation during its construction — absorbed FX at scale through precisely the allocation dynamics the industrialist is criticising, and its sponsors have talked publicly about the cost of FX friction in project execution.
[irp][irp][irp][irp][irp]
What Market-Determined Access Would Change
The distinction between allocation and market access is not cosmetic. Allocation-based FX supply is chronically opaque: buyers cannot see the queue, cannot price their expected acquisition timing, cannot hedge their currency exposure on defined terms, and cannot plan equipment procurement on a fixed timetable. Market-based access, in theory, solves all four problems by allowing buyers to meet sellers transparently at discoverable prices — the exact design principle the reform programme was built on.
Nigeria’s FX data shows why the demand matters. The Central Bank’s Q2 2026 Statistical Bulletin, published this week, put net foreign exchange flows at $22.50 billion for the quarter, the highest since Q4 2019, according to Nairametrics — a liquidity base that could, in principle, support genuine two-way markets for corporate buyers without the rationing queuing that allocation systems imply.
The Political Economy of the Ask
The CBN has resisted open-ended market access for capital-equipment buyers partly because unrationed windows are vulnerable to round-tripping, over-invoicing and speculative accumulation — abuses the bank has spent years policing through validation and returns frameworks. The design tension is real: honest importers want speed and transparency, while the regulator wants traceability. Software solutions to that tension exist — two-way quoting, pre-declared end-use, audit trails — and other currency markets have evolved them; whether the CBN’s next FX circular loosens access without re-creating the 2023-era arbitrage is the operational question.
The Gemeinschaft the industrialists occupy matters politically. If the country’s largest manufacturers, whose investment plans define the non-oil economy’s capex outlook, publicly push for market access just as the summit convenes, the central bank faces a measured pressure: ignore the push and risk FX frictions surfacing in earnings calls; concede without safeguards and riskleetcode arbitrage.
The Line Investors Should Watch
Three data streams will show whether the message lands. Corporate earnings calls this reporting season, where FX access friction shows up as capital-expenditure commentary. The NFEM’s own market depth — turnover concentration and bid-ask spreads recovered-or-not this quarter. And the CBN’s next policy FX announcements, which have historically moved in the window when industrial pressure and monetary stance converge. Dangote’s summit intervention makes that convergence explicit; the market will now watch whether follows.
Up next
NMDPRA Expands Gas Supply Access to Power and Fertiliser Plants Under New Network Code
The Nigerian Midstream and Downstream Petroleum Regulatory Authority has announced a new gas network code that widens third-party access to gas transportation infrastructure for power generation and fertiliser plants, in an aim to deepen domestic gas utilisation, THISDAY reported on October 26.
More in Economy
See all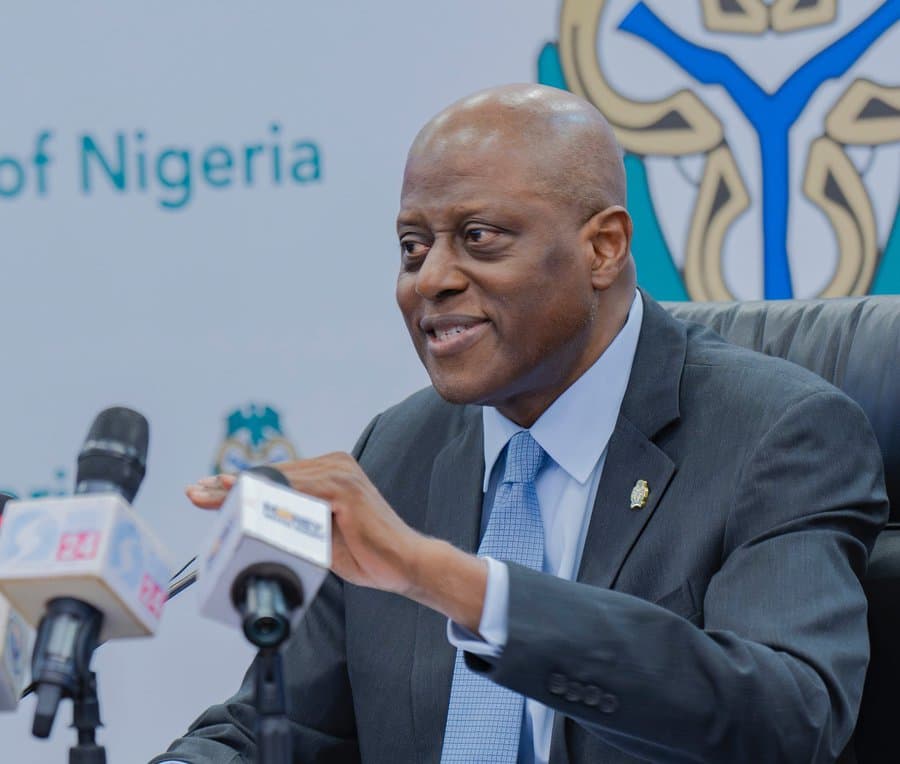
CBN Cuts Monetary Policy Rate to 23% in Its Largest-Ever Easing Move
The Central Bank of Nigeria lowered its benchmark interest rate by 350 basis points on September 22, 2026, the steepest cut on record, as inflation eased for a third straight month and reserves strengthened.

CBN resets policy rate to 23% and recalibrates lending corridor
The central bank described the 350-basis-point change as an operational realignment, not a shift in the underlying monetary-policy stance.
PENGASSAN Suspends Planned Nationwide Strike as Oil Firm Moves to Recall Sacked Workers
Oil workers under the Petroleum and Natural Gas Senior Staff Association of Nigeria resolved on Monday afternoon, October 26, to suspend a planned nationwide strike after an oil company moved to recall sacked workers, BusinessDay reported.
About the author
Tunde Balogun
Economics Correspondent
Tunde Balogun writes for BusinessPress.
More by Tunde Balogun